Independent agent and broker help
Local Licensed Medicare Agent help, explained before you call one
A Local Licensed Medicare Agent is someone the state has licensed to advise on and enroll you in Medicare coverage. What that person can actually show you depends on how they are appointed, and most people never think to ask. This page explains the difference, what the help costs, how to verify a license, and what to ask before you commit.
What a Local Licensed Medicare Agent actually does
The job is not finding you a plan. Plan lists are public, and anyone can view them at Medicare.gov. The job is working out which plan on that list fits the specific care you already receive.
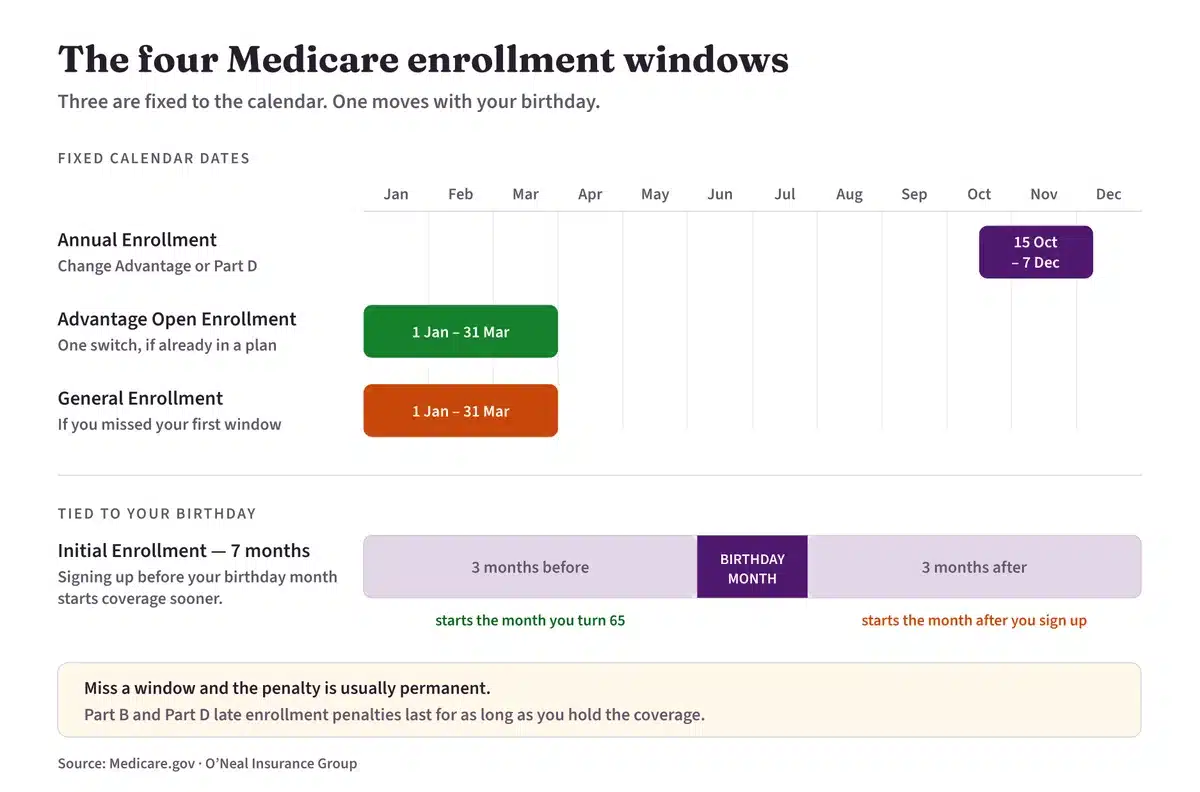
In practice that means checking your doctors against networks, running your prescriptions against formularies, comparing what you would pay when you use care, and explaining the enrollment windows so you do not create a lifelong penalty by accident.
The work, step by step
- Confirming each of your physicians and specialists participates in the plan network for the coming year
- Checking every prescription, with its dose, against each plan formulary and tier
- Comparing copays for the services you use and the annual maximum out-of-pocket
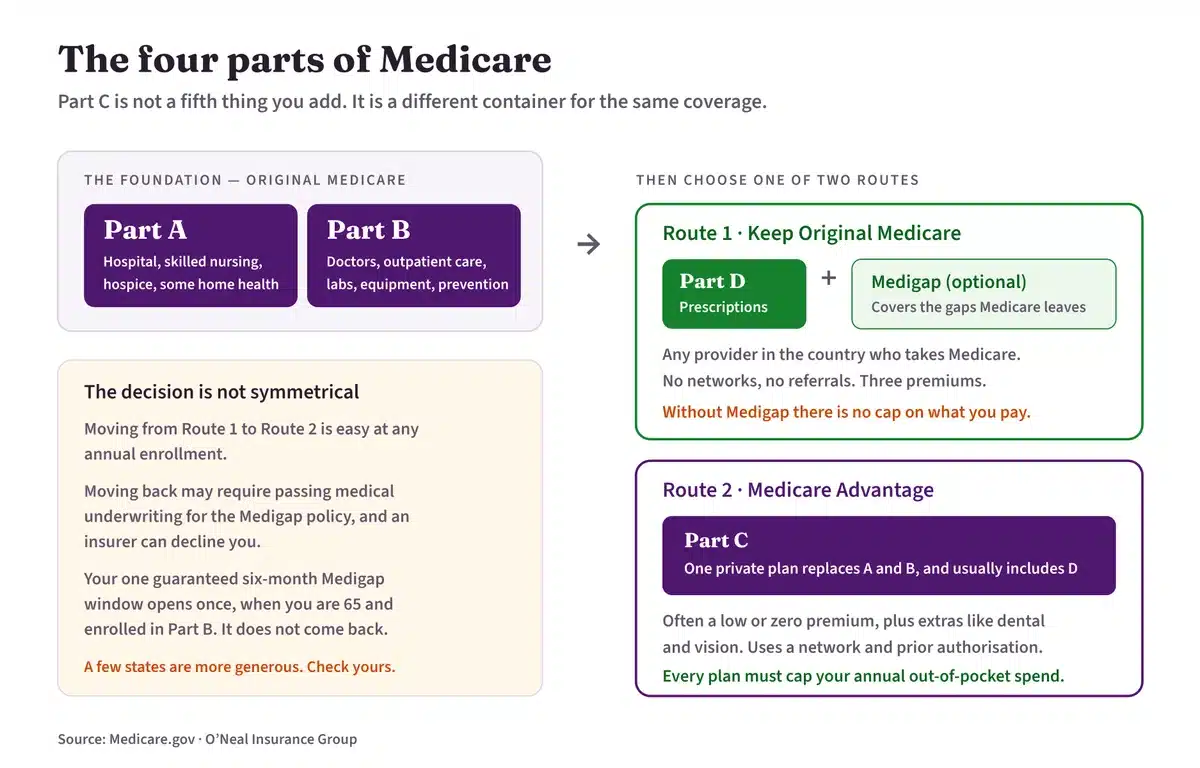
- Explaining how Original Medicare, Medicare Advantage, Medigap and Part D fit together
- Handling enrollment paperwork and remaining reachable when something changes
A good Local Licensed Medicare Agent will also tell you when your current plan is already the best fit. That answer is common, and hearing it is a sign you are talking to the right person.
Agent, broker, or captive: the distinction that matters
These words get used loosely, and the difference decides what you are shown.
A captive agent
Works for a single insurance company and can present only that company's plans. Nothing dishonest about it, but it is a narrower view than most people assume they are getting when they call a number from a commercial.
An independent agent or broker
Is appointed by several carriers and can compare across companies. This is what most people picture when they look for a Local Licensed Medicare Agent.
What no one can offer
No agent, independent or otherwise, offers every plan available in every area. Appointments and product availability vary. An honest agent tells you when something worth considering sits outside what they can offer, and points you to Medicare.gov Plan Compare or your State Health Insurance Assistance Program.
What a Local Licensed Medicare Agent costs you
Nothing additional. Agents are compensated by the insurance carrier when an enrollment occurs, and those amounts are capped by federal rule.
Because the compensation is regulated and broadly similar across carriers, there is no financial reason to steer you toward one company. Your premium is identical whether you enroll through an agent, directly with the carrier, or entirely on your own.
If anyone asks you to pay a fee to compare Medicare plans, stop and ask why. That is not how this works.
How to verify that an agent is licensed
Licensing is handled state by state, and every state maintains a public lookup. You are entitled to check, and a legitimate agent expects you to.
- Ask for the agent's full name and their license number in your state
- Search your state insurance department's public licensee database
- Confirm the license is active and covers health or life lines
- Check whether any disciplinary action is listed
Every state department of insurance is listed by the National Association of Insurance Commissioners. Nevada residents can search the Nevada Division of Insurance, and Illinois residents the Illinois Department of Insurance.
Agents selling Medicare Advantage and Part D must also complete annual federal training and be appointed by each carrier they represent.
Why local knowledge changes the answer
Medicare Advantage and Part D plans are approved and priced county by county. The plan a relative recommends from another state may not exist where you live, and if it does the network can be completely different.
A Local Licensed Medicare Agent knows which health systems dominate your area, which networks tend to include them, and which state rules apply to you.
State rules vary more than most people realize. Nevada gives Medigap policyholders a 60-day birthday window and allows a change of carrier. Illinois gives a 45-day window for ages 65 to 75 but restricts it to your existing insurer or an affiliate. Advice written for one state can be simply wrong in the other.
O'Neal Insurance Group is Medicare-licensed across 30 states and Washington, D.C., with offices in Las Vegas, Chicago, Hattiesburg and Ocean Springs. Our locations page lists the offices and the areas each one serves.
Questions worth asking any Local Licensed Medicare Agent
- Which carriers are you appointed with, and which ones in my county are you not able to offer?
- Will you check my specific doctors and my specific prescriptions before recommending anything?
- How are you compensated, and does it differ between the plans you are showing me?
- What happens if I have a problem in March, after the enrollment is finished?
- Can you explain why this plan fits me rather than the alternative?
The last one matters most. A clear, specific answer that references your own doctors and drugs is the difference between advice and a sales pitch.
Warning signs
Most agents are straightforward. The ones who are not tend to share the same tells, and they are easy to spot once you know them.
Pressure and false deadlines
Any urgency that is not a real Medicare enrollment period is manufactured. The genuine windows are fixed and public.
Asking for your Medicare number too early
There is no reason to collect it before you have chosen a plan. Guard that number the way you guard your Social Security number.
Other signals to take seriously
Be cautious if an agent presents one carrier while describing it as a full comparison, promises a specific benefit amount before confirming your county and plan year, discourages you from checking their license, or cannot explain what happens after enrollment.
Misleading Medicare marketing can be reported to 1-800-MEDICARE. If a call feels like pressure rather than information, that instinct is usually right.
Free alternatives worth knowing about
An agent is not the only source of help, and a trustworthy one will say so.
Every state runs a State Health Insurance Assistance Program offering free, unbiased counseling from people with no financial interest in your decision. Contacts are listed at shiphelp.org.
You can also call 1-800-MEDICARE directly, or compare every plan in your ZIP code yourself at Medicare.gov.
Many people use both: the official tools to see the full field, and a Local Licensed Medicare Agent to work through what the differences mean for their own doctors and prescriptions.
Ask before you decide
Questions about working with a Local Licensed Medicare Agent
Does a Local Licensed Medicare Agent cost anything?
No additional fee is charged to you. Agents may be compensated by an insurance carrier when an enrollment occurs, and your premium is the same either way.
Will an agent show me every plan available?
No one offers every plan available in every area. Availability depends on carrier appointment and product availability. Ask which carriers an agent cannot offer in your county.
Do I have to use an agent to enroll?
No. You can enroll yourself at Medicare.gov or by calling 1-800-MEDICARE, and free counseling is available through your State Health Insurance Assistance Program.
How do I check a license?
Ask for the agent's name and license number, then search your state insurance department's public database. A legitimate agent will expect the question.
Can we meet without an office visit?
Yes. Phone and online screen-sharing appointments are available, and many people prefer them because you can watch the comparison being built.
What if I am happy with my current plan?
Then keeping it is the right answer. An annual review is still worthwhile, because the plan changes each January even when your situation does not.
Important: Plan availability, benefits, networks and costs vary by county and by plan year. Nothing on this page is an offer of coverage or a statement of what any specific plan provides. We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your State Health Insurance Assistance Program to get information on all of your options.
Official resource
Why you get forty phone calls after filling in one form
This is the part of the industry nobody explains to the people it happens to, and understanding it is the fastest way to find a Local Licensed Medicare Agent rather than being found by a call center.
A great many websites that look like comparison tools are lead generators. Their business is not selling you a plan. It is collecting your name, telephone number and postcode and selling that record onward — sometimes to one agency, often to several at once.
That is why one form produces a fortnight of calls from firms you have never heard of. You did not sign up with them. Your details were sold to them, usually under a consent line you agreed to without reading, which is why the calls are not technically unsolicited.
The tell is in the small print near the submit button. If it says your information may be shared with partners, agents or marketing companies, that is a lead form whatever the page above it looks like.
What protects you
The rules are tighter than the volume of calls suggests. Cold calls, texts, robocalls, voicemails, social media messages and door-knocking are all prohibited when unsolicited. So is approaching people in car parks and lobbies. If contact arrives that way, the caller is breaking a federal rule before the conversation has even started.
Consent is also not permanent. You may tell any caller to remove you from their list, and ask which company they are calling from and which agency they represent. A Local Licensed Medicare Agent will answer both questions immediately. A call center reading a script often cannot.
Marketing and sales calls must be recorded and retained, which cuts in your favor: if a benefit was described to you on the telephone, there is a recording of it.
Call center, national agency, or someone down the road
All three can be properly licensed, and a Local Licensed Medicare Agent is not automatically better than the other two. The difference is not legitimacy, it is what each is set up to do well.
A large call center is built for volume. You will usually speak to a different person each time, the conversation follows a script, and the agent may be licensed in your state without ever having heard of the hospital you use. For a simple drug-plan change that is perfectly adequate.
A Local Licensed Medicare Agent is built for continuity. The same person handles the enrollment, the question in March and the review next autumn, and knows which systems in your county contract with which carriers — because they deal with the consequences when it goes wrong.
The practical test is not where the office is. It is whether the person can name the hospitals and specialist groups in your area without looking them up, and whether you will get the same person next time.
What happens after the enrollment is the real difference
Anyone can enroll you, a Local Licensed Medicare Agent included. The work that matters is spread across the following year.
A prescription that comes back more expensive than expected, and needs a tier exception or a preferred pharmacy. A specialist who leaves the network mid-year. A denial that should be appealed rather than accepted. An Annual Notice of Change in September that alters something material. A move, a new diagnosis, a spouse reaching 65.
None of that generates a new commission. Renewals are capped at half the initial amount and continue only while you stay enrolled, so the financial incentive is to keep you in a plan that works rather than to move you. That is the structural reason a Local Licensed Medicare Agent is worth having, and it is checkable rather than a matter of trust.
Ask any Local Licensed Medicare Agent one question before you commit: who do I ring in March, and will it be you? The answer tells you what kind of relationship you are entering.
And check the license, whoever you end up with. The National Association of Insurance Commissioners runs a free consumer lookup that shows whether a named person is licensed and what they are authorized to sell. Your state insurance department runs its own, usually with more detail including carrier appointments and any disciplinary history. It takes a few minutes and any Local Licensed Medicare Agent worth the name would rather you did it.
If something does go wrong, three separate places handle it and they do different jobs. 1-800-MEDICARE takes complaints about plans and about marketing conduct. Your state insurance department is the body that can actually discipline a producer’s license. And your State Health Insurance Assistance Program, at shiphelp.org, gives free counseling from people who sell nothing at all.
None of this makes any particular agency the right one. It simply means the questions worth asking a Local Licensed Medicare Agent are answerable, checkable and free — and an agency that treats them as an imposition has told you what you needed to know.
Ask it of us too. We would rather lose an enrollment to a better-suited agency than keep one that was never a good fit, and saying so in public is easier than proving it in private.
Check the source, then ask for personal help
Educational information is general. A licensed agent can help with plan comparisons; agents do not provide medical, legal, or official eligibility advice.
Personal guidance · No additional fee
Talk with a Local Licensed Medicare Agent who checks the details first
We start with your doctors and your prescriptions, then show you which plans in your county actually keep them.
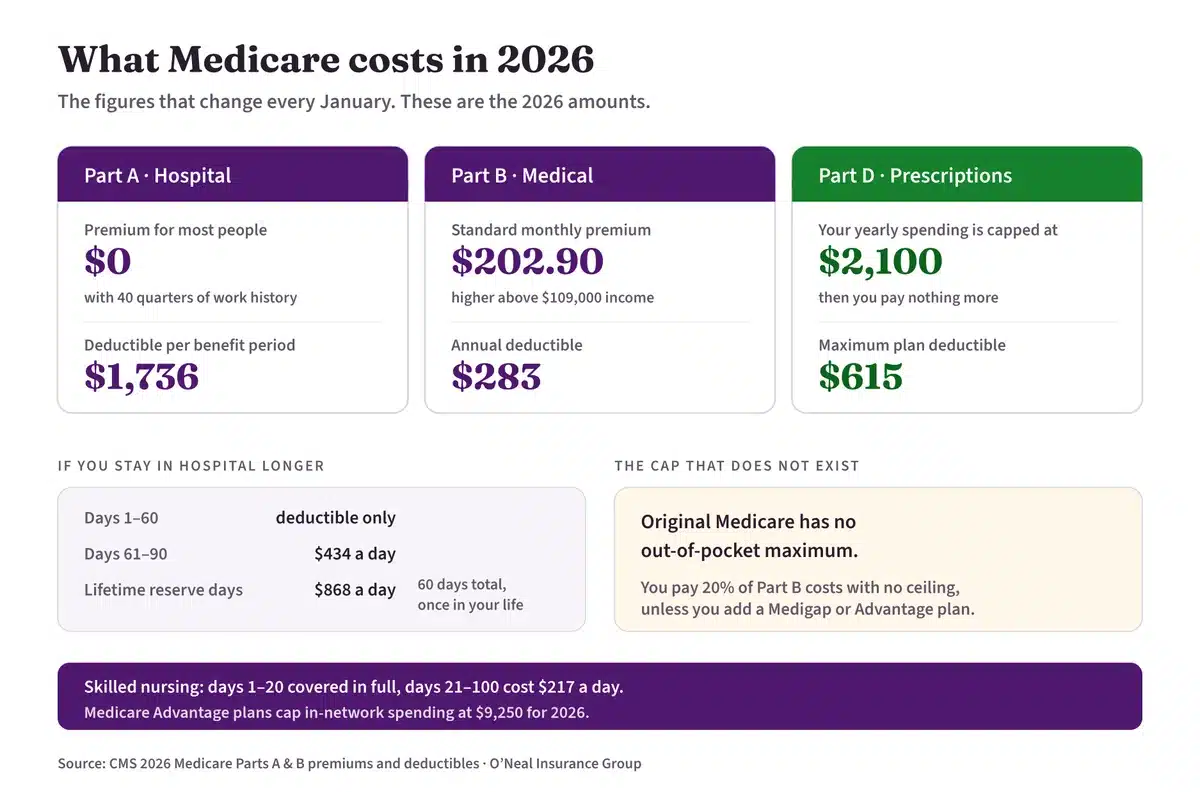
Medicare reference charts
The charts below cover the ground most questions start from.