Under-65 and family plans
Individual and family insurance
Individual and family insurance for people who are not yet on Medicare, including Marketplace health plans and Medicaid guidance.
What we can help with
Every individual and family insurance option below is explained without jargon. Call and we will walk through it together, at no cost to you.
Who individual and family insurance is for
Most of this site is about Medicare. This part is not. Individual and family insurance is what you buy when you are under 65, or when part of your household is, and there is no employer plan doing the job for you.
The households we see fall into a few groups. Self-employed people and contractors. Families where one parent has employer coverage that is too expensive to extend to everyone. People between jobs. Early retirees who left work before 65 and have a gap to bridge. And households where the income sits just above the Medicaid line, which is the most awkward position of all and the one most worth getting advice on.
If any of that describes you, the pages linked below go into detail. This one explains how the pieces fit together.
The health coverage routes, in order of who they suit
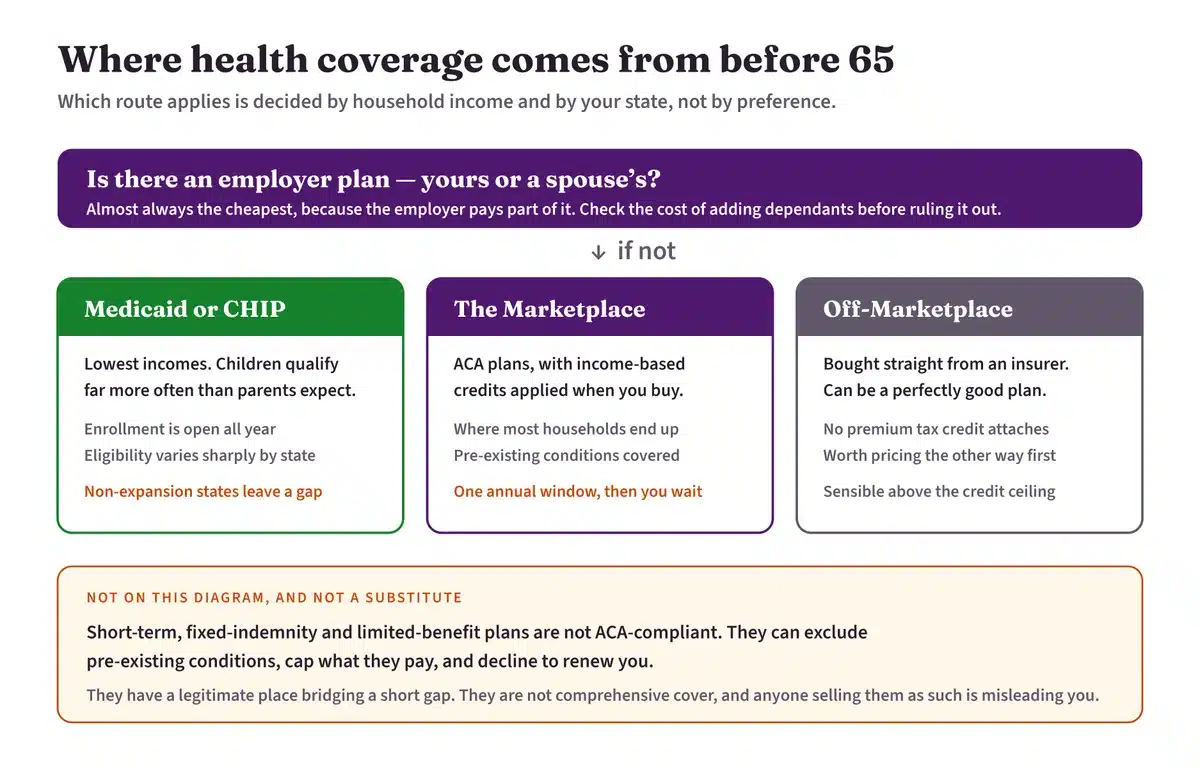
Comprehensive health cover is the foundation. Everything else in individual and family insurance sits on top of it.
An employer plan, yours or a spouse’s. Almost always the cheapest, because the employer pays part of the premium. Check whether adding dependants is affordable before ruling it out.
The Health Insurance Marketplace. ACA plans with income-based savings applied when you buy. This is where most individual and family insurance is purchased, and Open Enrollment runs from November 1 to January 15. Our individual and family health insurance guide covers metal tiers, cost-sharing reductions and how to choose.
Medicaid and CHIP. If household income is low enough, adults may qualify for Medicaid and children for CHIP — and children qualify far more often than parents expect. See our Medicaid page for eligibility groups, spend-down rules and the Medicare Savings Programs.
COBRA. Continuing an employer plan after leaving a job. It keeps your doctors and your deductible progress, and you pay the whole premium yourself, which is usually far more than a Marketplace plan with savings applied.
A household can legitimately be split across two of these at once. That is normal, not a mistake.
Cover that sits alongside a health plan
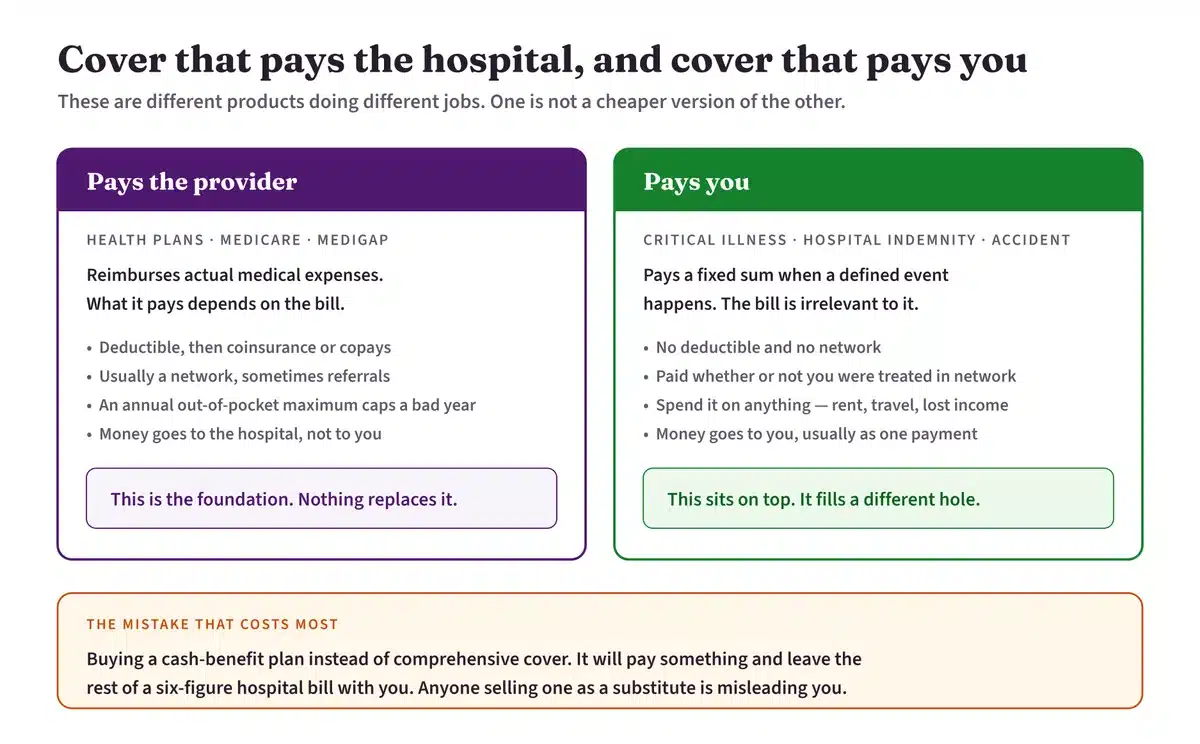
These do not replace comprehensive coverage. They pay for things a health plan leaves behind, and most of them pay cash directly to you rather than to a provider.
- Dental and vision insurance — routine care that health plans usually exclude for adults
- Hospital indemnity — a fixed amount per day in hospital, useful against a high deductible
- Critical illness — a lump sum after a covered diagnosis, for the costs treatment brings that nobody bills you for
- Life insurance — term, whole and final expense, which do different jobs at different stages
The rule we apply is simple. Fix the health plan first. Only then look at whether a supplemental policy closes a gap you would actually feel, and only buy it if the answer is yes.
How individual and family insurance fits together in practice
Take a household of four with self-employment income that varies by quarter. The realistic shape is often this: the two children qualify for CHIP and enroll year-round at little or no cost; the parents take a silver Marketplace plan, because cost-sharing reductions only attach to silver and can cut the deductible substantially; and a small hospital indemnity policy covers the deductible that remains.
That household is now on three separate products. It looks complicated written down, and it is usually several thousand dollars cheaper across a year than one family plan bought on premium alone.
The opposite mistake is just as common: buying a limited-benefit or short-term product because the monthly figure looked good. Those are not ACA-compliant. They can exclude pre-existing conditions, cap what they pay, and decline to renew you. They have narrow uses and they are not a substitute.
When someone in the household turns 65
This is the transition individual and family insurance handles worst if nobody plans it.
One person moving to Medicare does not end coverage for everyone else. The household usually keeps a Marketplace or employer plan for the under-65 members while the person turning 65 enrolls in Medicare separately. Dropping the whole family plan at that moment is a common and expensive error.
Two practical points. If you are on a Marketplace plan, report the change — premium tax credits are calculated for the people still on the plan, and leaving it unreported causes a reconciliation problem later. And if you are still working past 65 with employer coverage, get advice before delaying Part B, because the penalty for getting that wrong lasts for life. Our Medicare enrollment guide sets out which window applies.
What it costs to talk to us
Nothing, and there is no fee added to any policy. Plan prices are filed with regulators and are the same whether you buy through an agent or by yourself.
Being straight about the limits matters here. We are a licensed insurance brokerage. We do not represent every insurer, we cannot determine Medicaid eligibility — only your state can — and we do not give medical, tax or legal advice. Where a question belongs with a government office, we will say so and give you the number.
What we will do is check whether anyone in the household qualifies for Medicaid or CHIP before quoting anything, because free coverage beats a discounted premium every time.
Questions we are asked about individual and family insurance
Can I buy at any time of year? Comprehensive Marketplace coverage is generally limited to Open Enrollment, November 1 to January 15, unless a qualifying life event opens a Special Enrollment Period — losing other coverage, marriage, a birth or adoption, or a move. Most of those windows run 60 days and you will be asked to document them. Medicaid and CHIP are different: applications are accepted all year round.
Is a plan bought direct from an insurer cheaper than the Marketplace? Not usually, and often the reverse. Premium tax credits only apply to Marketplace plans, so a slightly lower list price off-Marketplace can cost far more once savings are taken into account. Price the Marketplace version first, then compare.
What if my income changes during the year? Report it. Individual and family insurance bought with a premium tax credit is reconciled against your actual income when you file, so an unreported raise turns into a bill and an unreported drop means you paid more than you needed to all year.
Do I have to use an agent? No. You can enroll yourself at HealthCare.gov or through your state’s own exchange, and free counseling is available from independent services that sell nothing. We are useful when the household is split across programs, when someone is approaching 65, or when you want the drug and provider checks done properly — and we cost you nothing either way.
Does individual and family insurance cover pre-existing conditions? ACA-compliant plans do, without exception and without a waiting period. Short-term and limited-benefit products frequently do not, which is the single most important difference between the two and the reason we ask what a plan actually is before comparing its price.
If your question is not here, ask it. There is no cost and no obligation, and individual and family insurance is the kind of decision that gets cheaper the earlier somebody looks at it with you.
The biggest change to individual and family insurance in years
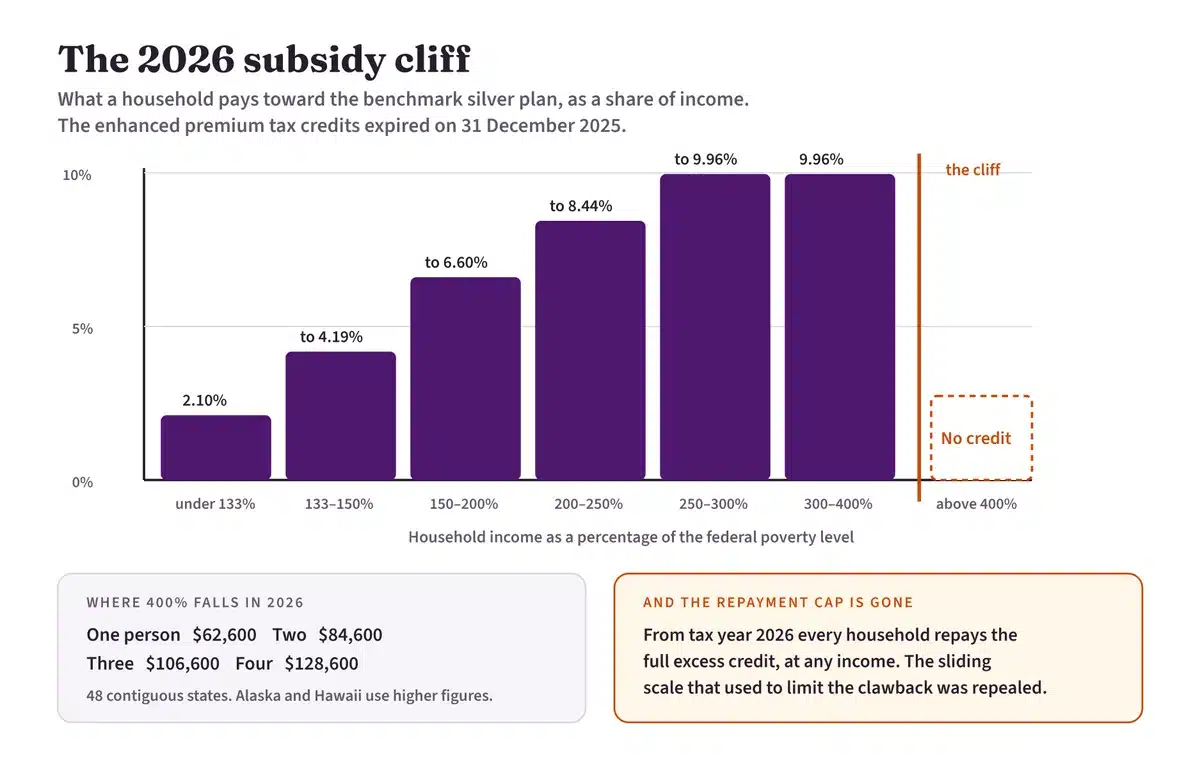
The enhanced premium tax credits that made Marketplace coverage unusually cheap from 2021 through 2025 expired on December 31, 2025 and were not extended. Plan year 2026 runs under the original rules written into the tax code, and anyone buying individual and family insurance feels it directly. If you have not shopped since 2024, the arithmetic on your household has changed, and not in your favor.
Two things went away together. The first was the removal of the income ceiling. From 2021 to 2025 there was no upper limit on who could qualify for help; households above four times the federal poverty level paid a capped percentage of income and received a credit for the rest. That ceiling is back, and it is a cliff rather than a slope.
The second was the lower contribution percentages at every income band. Households below 150 percent of the poverty level paid nothing for a benchmark silver plan. For 2026 they pay about 2.1 percent of income, and the required contribution at the top of the range is 9.96 percent.
Where the individual and family insurance cliff sits for 2026
Subsidy eligibility for individual and family insurance uses the poverty guidelines published the year before, so 2026 runs on the 2025 figures. In the 48 contiguous states, four times the poverty level works out at roughly $62,600 for one person, $84,600 for two, $106,600 for three and $128,600 for four.
One dollar of household income above those lines means no premium tax credit at all for 2026. Not a smaller credit — none. For a couple in their late fifties buying individual and family insurance, that can be the difference between a manageable premium and one that costs more than a mortgage payment.
This is the single most important thing to get right, and it is the reason to talk to someone before you file rather than after. Credits are paid in advance on estimated income and reconciled against actual income when you file your return. If you took advance credits all year and your actual income lands above the ceiling, you repay the entire amount, with no cap on the repayment. Self-employed households with variable income are the most exposed, and a good year can turn into a four-figure tax bill.
A second change compounds it, and it is not yet widely known. Until tax year 2025 the amount a household had to repay was capped on a sliding scale unless income landed above four times the poverty level. That cap was repealed for tax years beginning after December 31, 2025, so every household now repays the full excess whatever its income. A family at 180 percent of poverty that once faced a few hundred dollars of clawback now faces the entire difference, which makes a careful estimate worth real money to households well below the cliff as well as those near it.
Practical response: estimate conservatively, report income changes as they happen rather than at year end, and if you are close to the line, look at what legitimately reduces modified adjusted gross income — retirement contributions and health savings account contributions among them. That is a conversation for your tax preparer as much as your agent, and we will say so rather than pretend otherwise.
What is known about 2027
Congress has been arguing about restoring the enhanced credits all year, and nothing had been enacted as of late summer 2026. The clearest signal is administrative: the Internal Revenue Service published the indexed contribution table for 2027 in July 2026, and it still stops at four times the poverty level. A retroactive change remains possible. We would rather tell you the position is unresolved than quote you a number that moves.
Individual and family insurance and the Mississippi coverage gap
Mississippi has not adopted Medicaid expansion. Bills were filed again in the 2026 legislative session and none passed. That leaves a genuine gap beneath the Marketplace: premium tax credits begin at 100 percent of the poverty level, and adult Medicaid eligibility for parents and caretakers cuts off far below it, at around 19 percent of the poverty level. Adults without children and without a disability generally do not qualify at any income.
So a Mississippi household can earn too much for Medicaid and too little for a subsidy at the same time. Nevada and Illinois, where our other two offices sit, both expanded Medicaid, and coverage there runs continuously up to 138 percent of the poverty level before Marketplace subsidies take over. The same household income produces completely different individual and family insurance options depending on which of our offices you walk into.
Children are the exception worth knowing when individual and family insurance is out of reach. CHIP and children’s Medicaid reach well above the adult limits in every state, and applications are accepted all year rather than only during open enrollment. In practice a family in the gap often has covered children and uncovered parents, which is a partial answer rather than a good one.
Where you buy individual and family insurance depends on your state
Mississippi uses HealthCare.gov, the federal Marketplace. Nevada runs its own exchange, Nevada Health Link. Illinois moved off HealthCare.gov to its own state marketplace, Get Covered Illinois, beginning with plan year 2026 — so a Chicago household that enrolled at HealthCare.gov a year ago now starts somewhere else. If you have an old bookmark, replace it.
Open enrollment for 2026 ran from November 1, 2025 to January 15, 2026 on the federal Marketplace. Under a rule finalised in 2025, the federal window shortens from plan year 2027 to November 1 through December 15, with all coverage starting January 1. State-run exchanges may set their own dates within federal limits. That is a shorter runway than people are used to, and it is worth marking a calendar rather than relying on memory.
Outside those windows you need a qualifying life event — losing coverage, marriage, a birth or adoption, or a move — and you will be asked to document it. One route that used to exist has closed: the monthly special enrollment period for households under 150 percent of the poverty level was removed in 2025. Anyone still telling low-income families they can sign up for individual and family insurance any month of the year is working from outdated information.
If someone in the household has an employer offer
Affordability of employer coverage, which decides whether the rest of the household may buy subsidised individual and family insurance, is now tested separately for the employee and for the family. The employee is measured against the cost of self-only coverage; spouses and children are measured against the cost of the family plan. For 2026 the threshold is 9.96 percent of household income.
That fix, in place since 2023, means family members can qualify for Marketplace subsidies even when the employee’s own coverage counts as affordable, producing a split household where one person stays on the work plan and the rest buy individual and family insurance. It was a straightforwardly good strategy under the enhanced credits. With the cliff restored it needs re-running, because a family that did well out of it two years ago may now get nothing on the Marketplace side.
A note on short-term plans, which get marketed hard whenever premiums rise. Federal rules limit them to a three-month initial term and four months in total, but federal agencies announced in August 2025 that they would not prioritize enforcement pending new rulemaking, which leaves state law as the real constraint and it differs by state. These policies are not comprehensive coverage: they can exclude pre-existing conditions, cap benefits and decline to renew. They have a narrow legitimate use as a bridge between two known dates. They are not a substitute for individual and family insurance, and we will tell you so before we quote one.
Check any of this independently
All of it is verifiable at the source, free of charge.
- HealthCare.gov — the official Marketplace and plan finder
- Medicaid.gov — eligibility — the federal eligibility groups and state variation
- Medicaid.gov — CHIP — children’s coverage, open all year
- NAIC consumer tools — agent license and carrier complaint lookup
Related guides on this site
- Individual and family health insurance — Marketplace plans in detail
- Medicaid, CHIP and Medicare Savings Programs
- How we help — what an appointment involves and how we are paid
- New to Medicare and turning 65 — for the household member approaching the transition
- Book a no-cost appointment
Or call (877) 808-2900. Tell us who is in the household and roughly what the income looks like, and we will map the individual and family insurance options before anybody quotes you anything.
Personal guidance · No additional fee