Table of Contents
If you take one thing from this article: the only deadline that can permanently raise what you pay is the one around your 65th birthday. The rest, including important Medicare deadlines such as Annual Enrollment, are recoverable. Here they are in the order they’ll matter to you.
1. Your Initial Enrollment Period — seven months around your 65th birthday
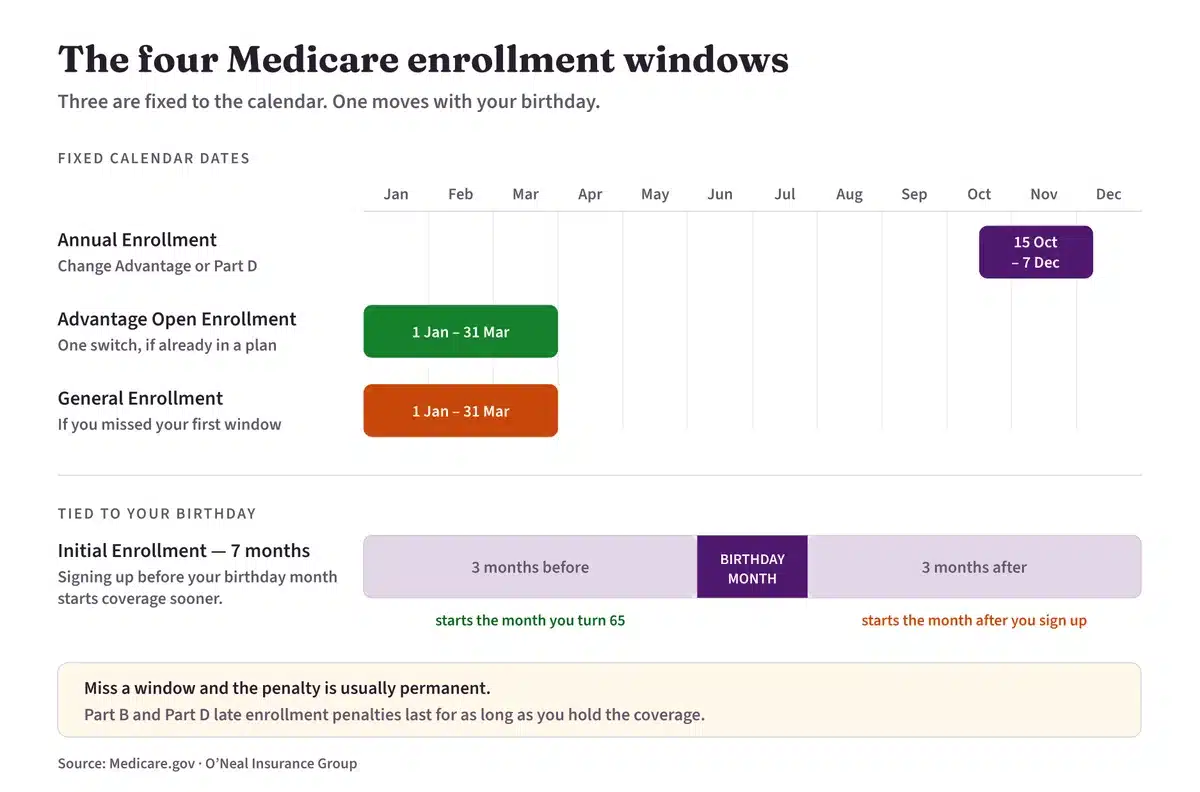
It opens three months before the month you turn 65, includes your birthday month, and closes three months after. Enroll in Part A and Part B in this window and there’s no penalty and no gap. Sign up in the three months before your birthday month and coverage starts the first day of your birthday month.
The exception that trips people up: if you’re still working and covered by a qualifying employer group health plan, you may be able to delay Part B safely. Whether that’s true depends on how many employees the company has and how the plan is structured — confirm it before your birthday, not after.
2. Your six-month Medigap open enrollment
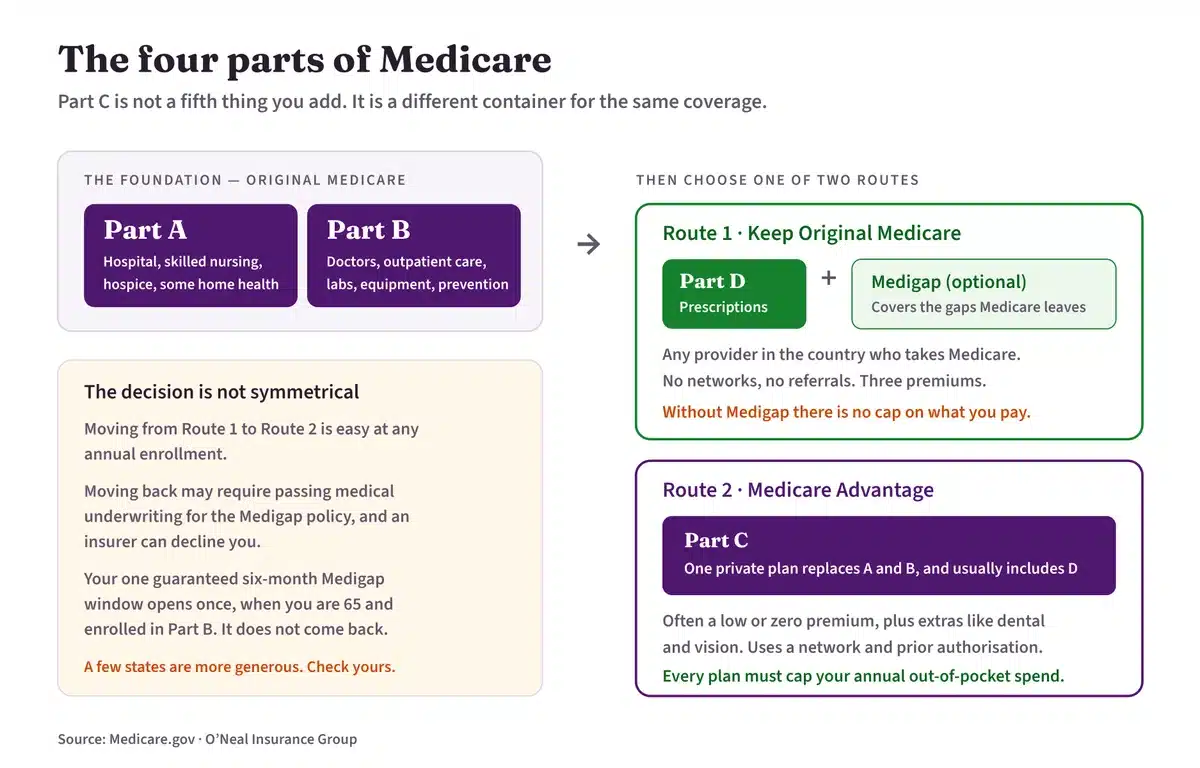
This is the most valuable window in Medicare, and almost nobody mentions it. For six months starting when your Part B takes effect, you can buy any Medicare Supplement policy sold in your state with no health questions asked. After it closes, most states let insurers underwrite — meaning they can charge more or decline you.
If you think you might ever want a Medigap policy, this is the window to use. It does not come back. More on how Medigap works →
3. Annual Enrollment — October 15 to December 7
Every year, this is your dependable chance to change Medicare Advantage or Part D plans. Whatever you choose takes effect January 1. It’s also the right moment to re-price your prescriptions, because formularies change every January — a plan that was cheapest last year often isn’t.
Miss it and you generally keep what you have for another year, unless you qualify for a Special Enrollment Period. Inconvenient, not permanent.
4. Medicare Advantage Open Enrollment — January 1 to March 31
If you’re already in a Medicare Advantage plan and January makes it obvious the plan doesn’t fit, you get one change during these three months: switch to another Advantage plan or return to Original Medicare. One change, not several.
A caution: returning to Original Medicare doesn’t guarantee you can buy a Medigap policy. Outside a guaranteed-issue right, that purchase may require underwriting.
5. The 63-day drug coverage rule
Go 63 days or more without Part D or other creditable prescription coverage after you’re eligible, and a late enrollment penalty is added to your Part D premium — roughly 1% of the national base premium for every month you went without, for as long as you have Part D coverage.
This is why people who take no medications still buy a minimum-premium plan. It’s inexpensive insurance against both a new prescription and a permanent surcharge. Coverage through the VA, TRICARE, or a retiree plan usually counts as creditable — but get that in writing.
What about all the other deadlines you’re hearing about?
If a postcard or a phone call is pressuring you toward a date that isn’t one of the five above, treat it as marketing. Real Medicare deadlines are published by CMS and don’t depend on calling a particular number today.
Special Enrollment Periods are the genuine exception to all of this. Losing employer coverage, moving to a new service area, gaining Medicaid or Extra Help, or a plan leaving your county can each open a window outside the normal calendar. If your life changed, ask — you may have more options than you think.
What you can actually change during Annual Enrollment
Annual Enrollment is the one window each year that is open to everybody on Medicare, whatever your circumstances. Between October 15 and December 7 you can do any of the following, and you may do more than one.
- Move from Original Medicare to a Medicare Advantage plan.
- Move from Medicare Advantage back to Original Medicare.
- Switch from one Medicare Advantage plan to another.
- Join a Part D drug plan, change to a different one, or drop it.
What Annual Enrollment does not hand you is a guaranteed right to buy a Medigap policy. That is a separate matter governed by your state’s rules, and it is the most common misunderstanding about the Annual Enrollment period.
Your Annual Enrollment checklist
Most people who lose money during Annual Enrollment do so by doing nothing. Carriers may change premiums, deductibles, copays, drug formularies and provider networks every January, and the plan that was cheapest for you last year often is not this year.
Read the Annual Notice of Change. Your carrier must send it by September 30, ahead of Annual Enrollment opening. It lists every change to your plan for the coming year in one document. It is dull, and it is the most valuable post you will receive all year.
Re-price your prescriptions. Put your real drug list, with doses, into Medicare’s Plan Compare tool. Formulary tiers move, and one drug changing tier can swing your annual cost by hundreds of dollars.
Confirm your doctors are still in network. Networks are refreshed for January. A physician who was in network in December may not be in January, and Annual Enrollment is your chance to respond to that.
Look at the out-of-pocket maximum, not the premium. On a Medicare Advantage plan, the annual out-of-pocket ceiling is what protects you in a bad year. The premium is what you notice; the ceiling is what matters.
Decide before December 7. The date is firm. Changes made during Annual Enrollment take effect January 1, and the last election you make is the one that counts.
Annual Enrollment is not the same as Open Enrollment
The two names get used interchangeably and they should not be. Annual Enrollment runs October 15 to December 7 and is open to everyone on Medicare. Medicare Advantage Open Enrollment runs January 1 to March 31, is open only to people already in an Advantage plan, and allows one change.
There is also the Health Insurance Marketplace open enrollment, which has nothing to do with Medicare but sits close enough on the calendar to confuse people every year. If you are on Medicare, the Marketplace is not where you shop.
Pressure tactics during Annual Enrollment
Annual Enrollment is the busiest marketing season in American health insurance, and the volume of calls, postcards and television advertising rises to match. A few rules protect you.
An agent may not cold-call you without permission, may not turn up at your door uninvited, and may not offer you a gift beyond a nominal value to enroll. Before discussing specific plans, an agent must have a Scope of Appointment recorded, and may only cover the product lines you agreed to.
Nobody from Medicare will telephone you during Annual Enrollment to ask for your Medicare number, your bank details or your Social Security number. If a caller does, hang up and report it to 1-800-MEDICARE.
And no legitimate deadline expires today. If a caller tells you it does, that is a sales technique, not a fact.
If you miss Annual Enrollment
Missing Annual Enrollment is inconvenient rather than permanent. You keep your current plan for another year unless a Special Enrollment Period opens for you.
Those are more common than people expect. Moving out of a plan’s service area, losing employer coverage, entering or leaving a nursing home, qualifying for Medicaid or Extra Help, or your plan withdrawing from your county each open a window outside Annual Enrollment. If your circumstances have changed, ask.
Free help during Annual Enrollment
You never have to pay for help with this. Every state runs a State Health Insurance Assistance Program staffed by trained counselors who sell nothing at all.
- Medicare.gov Plan Compare — every plan in your ZIP code with your prescriptions priced in
- SHIP National Technical Assistance Center — find your state’s free Medicare counseling service
- Social Security Administration — Extra Help with prescription drug costs
- CMS annual calendar — the official dates, published by the agency that sets them
If you would rather talk it through with a licensed agent who can see every plan in your area, O’Neal Insurance Group is on (877) 808-2900. Our help during Annual Enrollment costs you nothing — agents are paid by the carrier, not by you.
The exact dates for this cycle
Annual Enrollment runs from October 15 to December 7, 2026, and anything you change takes effect on January 1, 2027. Those dates are fixed in federal regulation rather than set by insurers, so they do not vary by state, plan or carrier.
Two details matter more than people expect. The deadline is the 7th, not the end of the month, and applications submitted on the last day are processed alongside everyone else’s. And if you make more than one change during the window, the last one submitted before the deadline is the one that takes effect.
Plan details for the coming year are published on October 1, ahead of Annual Enrollment, two weeks before Annual Enrollment opens. That fortnight is the best time to do the work: the information is complete, and nobody is competing for an appointment yet.
Why we suggest waiting until early October rather than late September
Plan data lands on October 1, but corrections follow. Benefit summaries and formularies occasionally go out with errors, and CMS and the carriers push fixes through in the first days of the month. Quoting from a document that gets corrected two days later is a real way to give someone the wrong answer in good faith.
This is one of the more concrete reasons to speak to an agent rather than rely on a printout. Someone working these plans daily sees the corrections; a beneficiary reading a single brochure does not.
A rule that changed, and old advice that is now wrong
The General Enrollment Period runs January 1 to March 31 for people who missed their initial window. It used to be that coverage bought during it did not begin until July 1 — a punishing gap that left people uninsured for months.
That changed. Coverage now begins on the first day of the month after you enroll. Any guide, forum post or well-meaning relative still telling you about a July start date is working from superseded rules, and the difference is up to six months of coverage.
The windows outside Annual Enrollment
Special Enrollment Periods exist for defined circumstances and most run 60 days from the qualifying event. The ones that come up most often:
- You move out of your plan’s service area, or into an area with plans your current one does not offer. Moving across a county line can be enough.
- You lose other coverage — an employer plan ending, COBRA running out, or losing Medicaid eligibility.
- You gain, lose or change Medicaid or Extra Help. This one is generous and repeatedly missed.
- Your plan leaves Medicare or stops serving your county. You receive a non-renewal notice and a window to choose again.
- You enter, live in or leave a nursing facility.
- A five-star plan is available in your area — you may switch to it once between December 8 and November 30, outside any other window.
You will be asked to document the qualifying event, so keep the letter, the lease or the termination notice. One route that used to exist has closed: the monthly special enrollment period for people under 150 percent of the federal poverty level was removed in 2025. Advice still offering year-round enrollment on that basis is out of date.
What changed in how agents may contact you
CMS has been tightening and then loosening marketing rules for several years, and the rules for the 2027 plan year removed some restrictions on the time and manner in which beneficiaries can have conversations with licensed agents.
Whatever the current rule, the protections that matter to you have not changed. An agent may not call you without permission you have given. You cannot be enrolled without your explicit consent. You may end any appointment at any time. And the commission an agent receives is capped by CMS at rates that do not vary meaningfully between plans, which is the structural reason a good agent has no financial motive to steer you.
If anyone tells you a deadline is tonight, that a benefit is about to be withdrawn, or that they need your Medicare number to check something before you have agreed to anything, those are the signs to end the conversation. Annual Enrollment is when that pressure peaks.
What makes the appointment quick
Three things turn a long conversation into a short one: your county, your prescriptions with doses, and the doctors and hospitals you intend to keep. With those, a county’s worth of plans narrows to a short list in a single sitting. Without them, the honest answer to most questions is that it depends.
What happens if you do nothing
In most cases your plan renews automatically, which feels like the safe choice and often is not. The plan that renews is next year’s version of it, with next year’s formulary, network and costs. Doing nothing during Annual Enrollment is a decision to accept changes you have not read.
If your plan is leaving Medicare or leaving your county, you receive a non-renewal notice instead, and doing nothing then can leave you back on Original Medicare with no drug coverage and a penalty accruing. Those notices arrive in the same week as a great deal of marketing post, which is precisely why they get missed.
Checking takes one conversation, and Annual Enrollment is the window in which it is free to act on what you find. Annual Enrollment exists so that the decision is yours rather than the calendar’s.
One last practical point about Annual Enrollment: the busiest weeks are the last two. If you want unhurried time with someone, the first half of the window is when it exists.
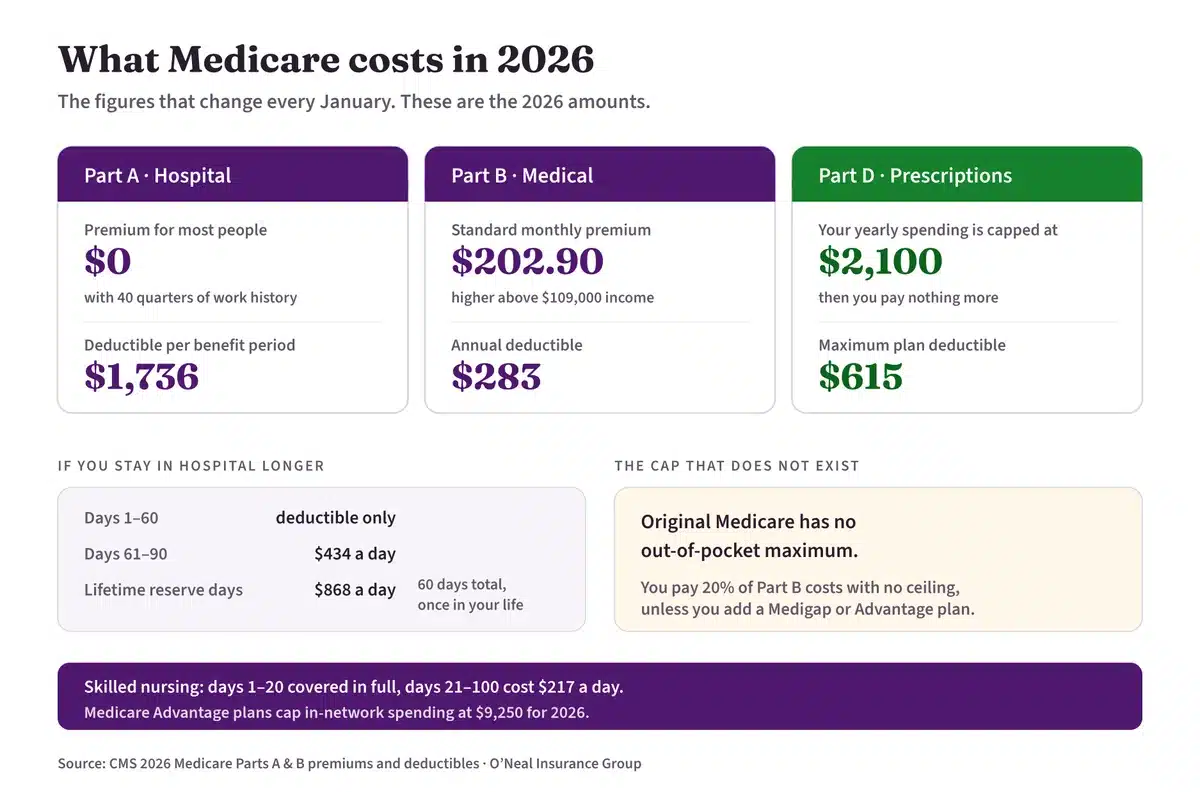
Medicare reference charts
One more chart that answers a question we get constantly.
Related guides on this site
- Medicare Simplified — the full beginner’s guide, start to finish
- What Medicare Advantage costs — premiums, copays and the out-of-pocket ceiling
- How Medigap works — and why its own window matters more than Annual Enrollment
- Book a no-cost appointment before December 7
Not sure which window you’re in?
Tell us your birthday and your situation and we’ll tell you exactly which dates apply to you — no cost, no obligation.
This article is general information, not advice about your specific situation, and figures reflect the 2026 plan year. For official information, see Medicare.gov’s enrollment pages or call 1-800-MEDICARE.