
Medicare plans Las Vegas residents can join in 2026
The Medicare plans Las Vegas residents can enroll in fall into three groups: Original Medicare paired with a Medigap policy, Medicare Advantage, and standalone Part D drug coverage. About 16.0% of the city’s 679,817 residents are 65 or older — roughly 109,000 people — and across Clark County the figure is 17.0% of 2.4 million.
That scale matters. Clark County is one of the most competitive Medicare Advantage markets in the country, which is good for premiums and confusing for everyone trying to choose. This page sorts the Medicare plans Las Vegas carriers actually sell into something you can decide between.
O’Neal Insurance Group is a Black-owned independent agency licensed in Nevada. We compare the Medicare plans Las Vegas offers alongside those in North Las Vegas, Henderson, Summerlin and Boulder City. Our help costs you nothing — agents are paid by the carrier, never by you. Call (877) 808-2900.
The Nevada birthday rule — the thing most guides get wrong
Nevada is one of a small number of states with a Medigap birthday rule, and it is unusually generous. Under Assembly Bill 250, effective January 1, 2022, if you already hold a Medicare Supplement policy, you get a window that opens on the first day of your birthday month and stays open for at least 60 days.
During that window you may move to a policy with the same or lesser benefits — and, importantly, you may move to a different insurance company, not just a different plan from your current one. No medical underwriting applies. The Nevada Division of Insurance confirmed this when the rule took effect.
Two limits are worth knowing. The rule applies to people who already hold a Medigap policy, so it is not a way into Medigap from Medicare Advantage. And it excludes so-called innovative benefits — dental, vision, hearing and gym memberships bolted onto a Medigap plan.
This single rule changes the arithmetic on the Medicare plans Las Vegas seniors should consider. In most states, choosing Medigap at 65 is close to a one-way door because carriers can underwrite you later. In Nevada, an annual escape hatch exists for anyone already inside.
Networks and Clark County hospitals
The single biggest difference between the Medicare plans Las Vegas carriers offer is which hospitals and physician groups are in network.
University Medical Center of Southern Nevada is the state’s only Level I trauma center. Sunrise Hospital and Medical Center, the Valley Health System hospitals across the valley, Southern Hills, and St. Rose Dominican in Henderson make up most of the rest of the acute-care map.
Physician groups matter just as much here, and often more. Several of the Medicare plans Las Vegas insurers sell are built around a specific medical group, and leaving that group means leaving the plan. Check the group, not just the hospital name.
If you live in Summerlin or Henderson and your specialists are on the other side of the valley, a plan’s map is worth studying before its premium is. Driving 40 minutes for a routine appointment gets old quickly.
Medicare Advantage: the Medicare plans Las Vegas enrollees pick most
Advantage plans dominate enrollment in Clark County. Dense population, a concentrated provider market and heavy competition let carriers offer zero-premium plans with extras attached.
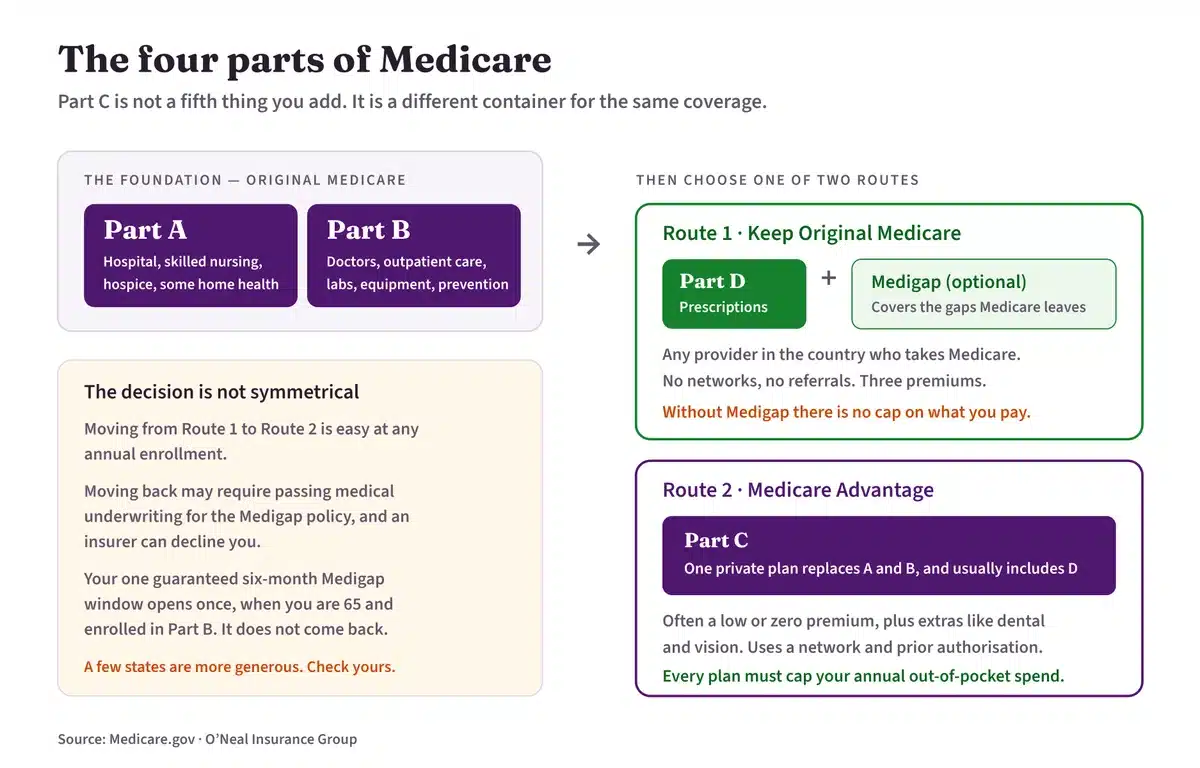
HMO plans keep you in network except in an emergency and usually ask you to name a primary care physician who coordinates referrals. PPO plans cost more and let you go out of network at a higher share of cost.
Every Advantage plan carries an annual out-of-pocket maximum. Original Medicare on its own does not. That ceiling is the real protection the plan gives you, and across the Medicare plans Las Vegas carriers file it varies by thousands of dollars.
The advertised extras — over-the-counter allowances, transport, fitness memberships, flex cards — are real, but they are the last thing to choose on. Get the network and the drug coverage right first, then use the extras as a tiebreaker between Medicare plans Las Vegas residents would otherwise be equally happy with.
A special note for people who spend part of the year elsewhere. Las Vegas has a large population of seasonal residents and recent arrivals from California and the Midwest. An HMO tied to a Clark County network handles out-of-area care very differently from a PPO or from Original Medicare with Medigap.
What the Clark County plan mix actually looks like
The ability to offer diverse plan options sets independent Medicare Advantage plan insurance agents near me apart from captive agents tied to single carriers. We work with multiple insurance companies to ensure you see all available options: Aetna, Alignment Health Plan, Anthem, Banner Health, BlueCross BlueShield of Illinois, Cigna, Clover Health, Devoted Health, Essence HealthCare, GTL, Guarantee Trust Life Insurance Company, Humana, KCA, Kelsey Care Advantage, Molina HealthCare, Mutual of Omaha, Physicians Mutual, Scan Health Plan, Select Health, United Healthcare, Wellcare, and Zing Health.
Clark County offers different plan structures with varying enrollment patterns. HMO plans average USD 0.50 in monthly premiums, with 90,201 beneficiaries enrolled, while PPO plans average USD 4.58 in monthly premiums, with 32,969 enrollees . HMO-POS plans, which combine network requirements with some out-of-network flexibility, average USD 0.00 monthly premiums and serve 59,769 members.
The most popular plan in Clark County is Humana Gold Plus H6622-056 (HMO) with 40,089 enrollees, followed by AARP Medicare Advantage Essentials ValueRx NV-5 (HMO-POS) with 30,506 members. However, popularity doesn’t equal the best fit for your situation. An agent with broad carrier access can compare these top plans against lesser-known options that might better match your doctors, prescriptions, and budget.
Specialized populations require particular attention. We serve Dually Eligible Beneficiaries who qualify for both Medicare and Medicaid through C-SNP and D-SNP plans. Medicare Part B Giveback Plans can reduce your monthly Part B premium. New to Medicare Beneficiaries need Guidance through initial enrollment periods, while Veterans may need coordination between V.A. benefits, Tricare Health Insurance for military retirees, and Medicare coverage.
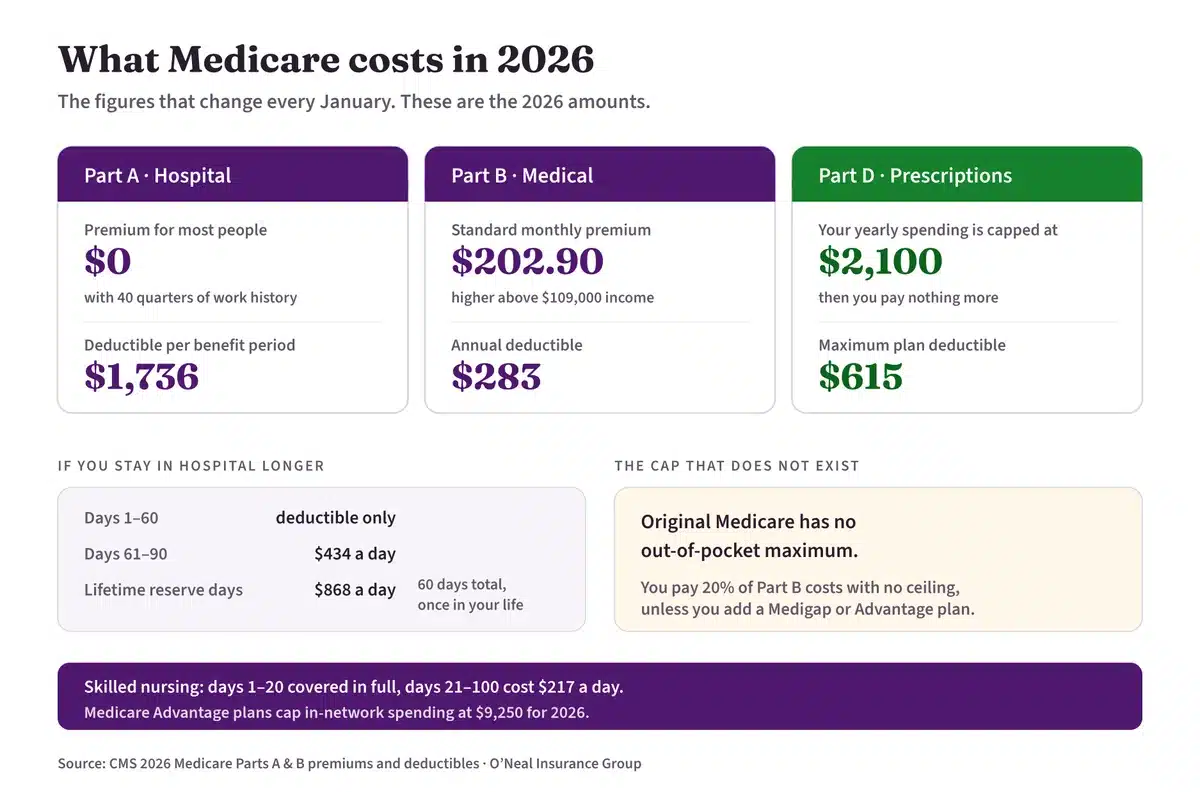
Average maximum out-of-pocket costs in Clark County are USD 3,025.00, with a 2026 maximum of USD 9,250.00 . Average Part D deductibles reach USD 332.57. These figures vary considerably by plan type, making side-by-side comparisons necessary rather than optional.
Drug coverage and what it costs in 2026
Prescription coverage is where choices among the Medicare plans Las Vegas offers most often go wrong. No plan is good or bad for drugs in the abstract; it is good or bad for your particular list.
Bring the bottles, or a written list with doses. Then check three things: whether each drug is on the plan’s formulary, which tier it sits on, and whether the plan requires step therapy or prior authorization before it pays.
The 2026 rules help. No Part D plan may charge a deductible above $615, and once you have spent $2,100 out of pocket on covered drugs your cost for the rest of the calendar year is zero. The Medicare Prescription Payment Plan lets you spread that amount over monthly installments rather than facing it in January.
If your income is limited, Extra Help through Social Security can cut premiums and copays substantially. A large number of people who qualify never apply, and checking costs nothing.
How to narrow the Medicare plans Las Vegas offers to a shortlist
Start with your doctors
Name every physician you want to keep, then check each one against the plan directory — and confirm the medical group, not just the individual. This eliminates most of the Medicare plans Las Vegas carriers offer within a few minutes.
Then your prescriptions
Two plans with identical premiums can differ by thousands of dollars a year once your actual medications are priced in. This is the step people skip and later regret.
Then how you want to pay
Medicare Advantage keeps the monthly cost low and charges you when you use care. Medigap does the opposite: a higher predictable premium, very little at the point of service. Neither is better in general; it depends on your cash flow and your tolerance for surprise bills.
Commissions are set by CMS and are identical across carriers for the same product line, which is why an independent broker can compare every option without a financial reason to steer you.
When you can enroll or switch
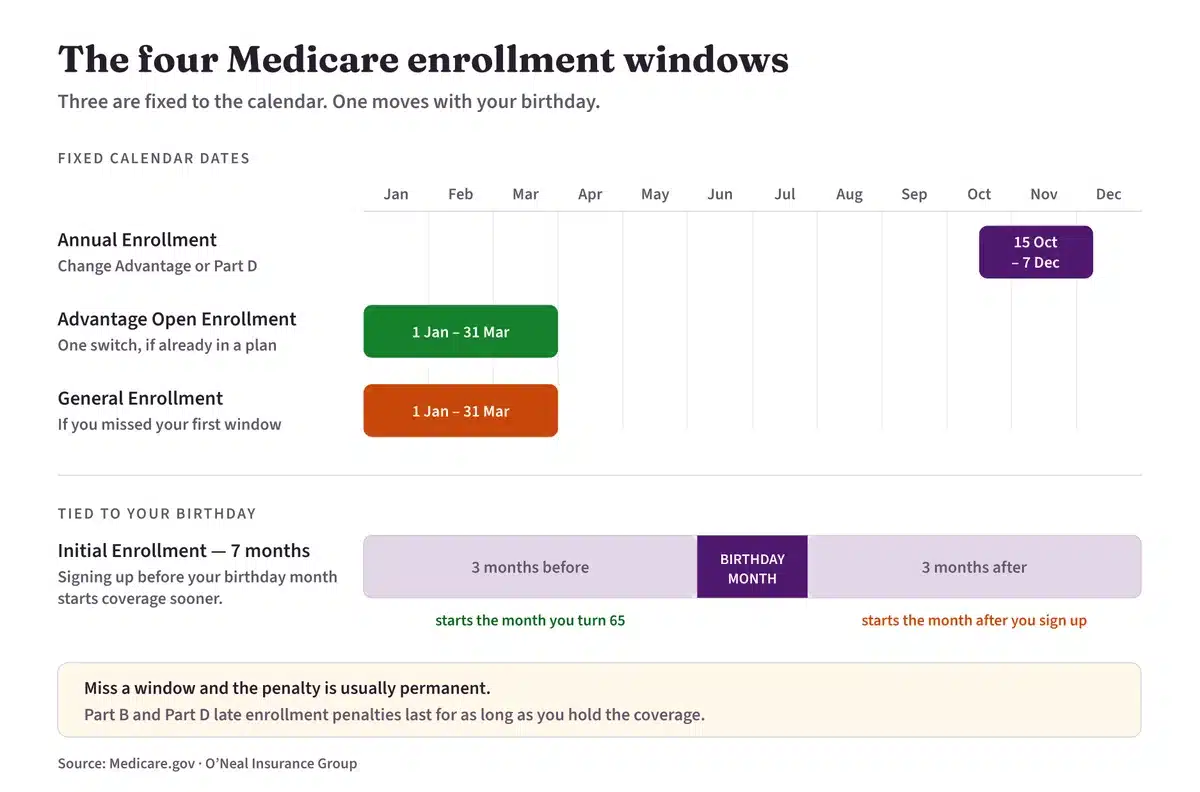
Initial Enrollment Period. Seven months centred on the month you turn 65. Sign up in the three months before your birthday month and coverage starts on the first of that month.
Annual Enrollment Period, October 15 to December 7. Anyone can switch between Original Medicare and Medicare Advantage, change Advantage plans, or change Part D plans. Changes take effect January 1.
Medicare Advantage Open Enrollment, January 1 to March 31. If you are already in an Advantage plan, you get one chance to move to another Advantage plan or return to Original Medicare with a Part D policy.
Your Nevada birthday window. Separate from all of the above, and only for existing Medigap policyholders. It opens on the first day of your birthday month.
Special Enrollment Periods. Moving into or out of Clark County, losing employer coverage, entering or leaving a nursing home, or qualifying for Medicaid or Extra Help each open a window outside the normal calendar. Given how many people move to Las Vegas after retiring, the relocation trigger comes up constantly.
Mistakes to avoid in Clark County
Missing your Initial Enrollment Period is the expensive one. Part B and Part D late penalties are permanent, and none of the Medicare plans Las Vegas carriers sell can undo one once it attaches.
Assuming employer coverage counts is the second. Some group plans are creditable coverage and let you delay Part B without penalty; many small-employer plans are not. Get it confirmed in writing.
Renewing without reading is the third. Formularies, networks and copays change every year, and the Annual Notice of Change that arrives each September is where the carrier discloses it. Half an hour reviewing the Medicare plans Las Vegas carriers offer each autumn is well spent.
Enrolling from a television advert is the fourth. Those numbers route to national call centers that may represent a single carrier. Choosing among the Medicare plans Las Vegas actually has takes someone who knows which local medical groups sit in which network.
Clark County is a majority-Advantage market, and that cuts both ways
CMS enrollment data for May 2026 counts 426,638 Medicare beneficiaries in Clark County. Of those, 241,971 — about 56.7 percent — hold a private plan rather than Original Medicare, and 184,667 remain on the traditional route.
| Area | Medicare beneficiaries | In a private plan |
|---|---|---|
| Clark County | 426,638 | 56.7% |
| Nevada | 628,268 | 52.1% |
| United States | 70,465,854 | 51.2% |
Clark County runs five and a half points ahead of the country and nearly five ahead of its own state. Among the Medicare plans Las Vegas residents can choose from, private plans are the majority choice by a clear margin.
What that gets you
Carriers compete hardest where the members are. A market this size and this concentrated draws a lot of filings, which is why the Medicare plans Las Vegas carriers offer include a wide field of zero-premium options and generous extra benefits — dental allowances, over-the-counter cards, transport, gym membership.
It also means real choice on networks. In thinner markets a county might have three or four plans worth considering. Here the shortlist is built by elimination rather than by scarcity.
And what it costs
The trade is that extras are the loudest part of the marketing and the least important part of the decision. A dental allowance is worth a few hundred dollars a year. A network that excludes your oncologist, or an out-of-pocket maximum of $9,250 in network, is worth a great deal more.
The second cost is subtler. In markets where most people have moved to private plans, the traditional route gets discussed less, quoted less and assumed to be unaffordable. It often is not. Some 184,667 Clark County residents are still on Original Medicare, which is more people than live in most Nevada cities, and supplement carriers remain active here precisely because of it.
So get both numbers. Price a supplement with a standalone drug plan alongside the strongest of the Medicare plans Las Vegas carriers are advertising, and compare a healthy year against a difficult one rather than premium against premium.
One county, one plan list, a very spread-out valley
Clark County files one plan list. Henderson, North Las Vegas, Summerlin, Boulder City and the whole valley draw from the same menu, so a neighbor’s recommendation is at least available to you — which is not true in metros split across several counties.
What differs is not the menu but the driving. A plan can satisfy its network adequacy requirement for a county this large while putting your nearest in-network cardiologist a long way from your house. Distance standards are calculated by specialty, and Clark County covers a lot of ground.
So check mileage, not just membership. Find the nearest in-network provider for each specialty you actually use, and note the drive in July traffic rather than on a map.
Two more Clark County specifics are worth raising. About 62,703 beneficiaries here — roughly 14.7 percent — hold Medicare and Medicaid together, so the Medicare Savings Programs are worth checking before you compare anything. And a great many households here spend part of the year elsewhere, which is a network question rather than a premium one: ask what a plan pays for planned care outside its service area, and whether it offers a visitor or traveler benefit.
Answer those two questions about the Medicare plans Las Vegas carriers file first. They narrow the Medicare plans Las Vegas offers faster than any comparison table, and they are the questions the advertising never asks.
Book the review before autumn rather than during it. Plans are filed annually, and comparing the Medicare plans Las Vegas carriers have submitted is an unhurried job in August in a way it never is in November, when the mail arrives all at once and every call center in the valley is busy.
Bring the medication list and the doctors. Those two things decide more about the Medicare plans Las Vegas offers than any other detail on the page.
Check any of this independently
Before you commit to one of the Medicare plans Las Vegas carriers offer, get a second opinion from an organization with no commission at stake.
- Medicare.gov Plan Compare — every plan sold in your Clark County ZIP code, with your prescriptions priced in
- Nevada SHIP — free, unbiased counseling from the Aging and Disability Services Division, 1-800-307-4444
- Nevada Division of Insurance — Medigap guidance and the annual premium comparison guide
- Social Security Administration — Extra Help with prescription drug costs
- Clark County is a majority-Advantage market
- One county, one plan list, a very spread-out valley
Related guides for southern Nevada
- Medicare plans in Nevada — the statewide picture
- North Las Vegas — a different network footprint on the same valley
- Las Vegas Medicare agents near you and broker help in Las Vegas
- Anthem Medigap in Las Vegas, SCAN Health Plan and Select Health — carrier-by-carrier detail
- What Medicare Advantage costs and how Medigap works