New York Medicare guidance
Medicare plans New York residents can compare, county by county
The Medicare plans New York residents can join are approved county by county, and New York guarantees Medigap access all year at community-rated premiums. O'Neal Insurance Group helps New Yorkers compare Medicare and other insurance choices available where they live. Licensed agents can explain county service areas, provider networks, prescriptions, costs, and eligibility in straightforward language.
- Independent Medicare guidance
- Your own personal broker contact
- No-cost consultation
- Licensed agent support
Medicare Guidance for New York City, Upstate, and Long Island
New York's health care patterns change quickly between the five boroughs, Long Island, the lower Hudson Valley, western New York, the Capital Region, and smaller upstate communities. Medicare Advantage and Special Needs Plans use county service areas. New York City is one incorporated city across five county-equivalent boroughs, so the borough county—not only the words “New York City”—matters during a plan search.
Your Own Personal Medicare Agent Broker can help organize the comparison. A Need Analysis records doctors, hospitals, pharmacies, prescriptions, expected care, budget, and priorities. A Scope of Appointment, when required, identifies the Medicare product categories you agree to discuss. Insurance agents use these steps to understand coverage requirements and comply with federal Medicare marketing rules. Neither is an enrollment application.
Confirm every provider's practice location and hospital affiliation. Networks, drug formularies, costs, prior-authorization rules, and supplemental benefits can change annually, so review coverage each year.
Work with a Medicare Health Insurance licensed insurance agents broker serving New York for a current county-and-ZIP comparison.
Medicare, Health, Life, and Dental Insurance Help in Major New York Cities
- New York City — 8,584,629. The city spans Kings, Queens, New York, Bronx, and Richmond counties; use the residential borough county and exact ZIP code.
- Buffalo — 274,613. Erie County residents should check local health systems, medical groups, and pharmacy networks.
- Yonkers — 212,603. Westchester County options may differ from the Bronx or New York City even when providers overlap.
- Rochester — 206,108. Monroe County residents should verify local hospital systems, specialists, and prescriptions.
- Syracuse — 144,896. Onondaga County choices should be checked for local networks and regional referral patterns.
- Albany — 101,698. Capital Region care crosses county lines, so residents should confirm each provider and facility.
- New Rochelle — 85,864. Westchester County service areas and networks should be verified separately from nearby Bronx County.
- Mount Vernon — 72,304. Residents should check Westchester plan rules for doctors used in the city or nearby boroughs.
- Schenectady — 69,471. Schenectady County residents should verify Capital Region hospitals, pharmacies, and specialists.
- Utica — 62,978. Oneida County residents should examine local access and travel for higher-level specialty care.
Population source: U.S. Census Bureau Vintage 2025 incorporated-place estimates, July 1, 2025.
Reviewing Medicare plans New York county by county
- Kings County — 2,653,963: Brooklyn residents should verify MA, D-SNP, C-SNP, provider-network, prescription, and supplemental-benefit availability by ZIP and plan.
- Queens County — 2,358,182: Queens residents should check medical groups, hospitals, pharmacies, and cross-borough access.
- New York County — 1,664,862: Manhattan residents should confirm exact provider participation; a hospital name alone is not enough.
- Suffolk County — 1,546,090: Huntington, Brookhaven, Islip, Babylon, and Riverhead area residents should review Long Island networks and distances.
- Bronx County — 1,406,332: Bronx residents should verify local systems and whether providers in Manhattan or Westchester are contracted.
- Nassau County — 1,398,939: Hempstead, North Hempstead, Oyster Bay, Long Beach, and Glen Cove area residents should compare county offerings and networks.
- Westchester County — 1,015,743: Yonkers, New Rochelle, Mount Vernon, and White Plains residents should check county service areas and New York City provider access.
- Erie County — 946,741: Buffalo, Amherst, Cheektowaga, and Tonawanda residents should review western New York systems and pharmacies.
- Monroe County — 750,506: Rochester, Greece, Irondequoit, and Brighton residents should verify local networks and drug formularies.
- Richmond County — 501,290: Staten Island residents should use Richmond County when checking choices and cross-borough care.
Population source: U.S. Census Bureau Vintage 2025 county estimates, July 1, 2025.
Understanding the Medicare plans New York offers
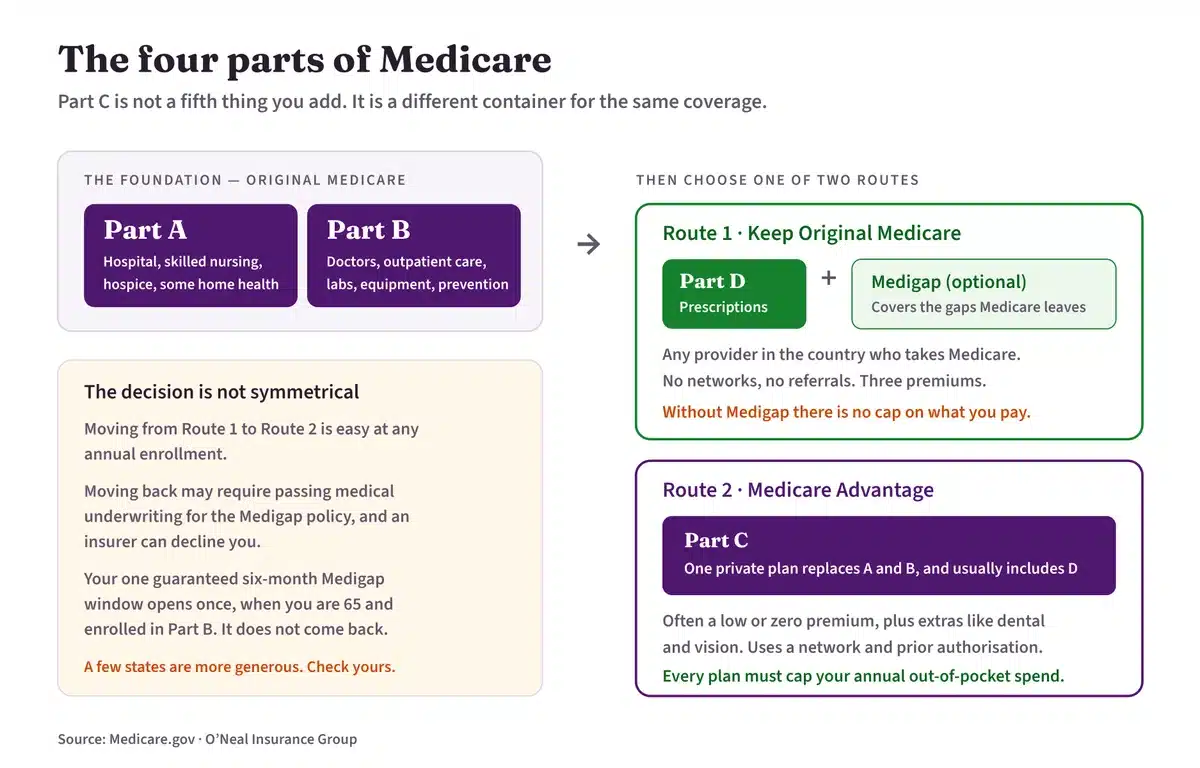
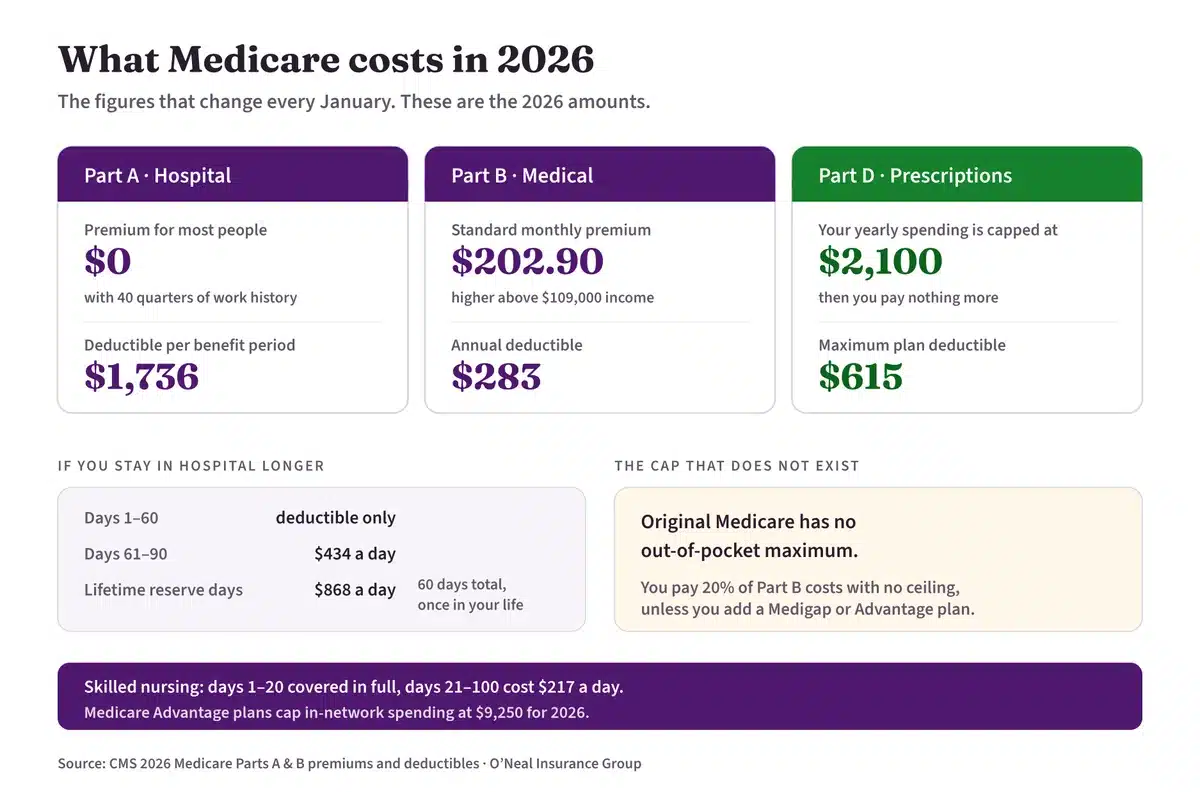
Original Medicare includes federal Part A and Part B. Part A generally covers inpatient hospital care, skilled nursing facility care, hospice, and certain home health services. Part B generally covers physicians, outpatient services, preventive care, and durable medical equipment. Original Medicare has no annual Part A/B out-of-pocket maximum.
Medicare Advantage (Part C) is private Medicare-approved coverage delivering Part A and B benefits; many plans include Part D. A stand-alone Part D plan can be paired with Original Medicare. Medicare Supplement (Medigap) helps pay certain Original Medicare cost sharing and does not work with Medicare Advantage. Hospital indemnity and critical illness policies are separate limited-benefit products, not Medicare.
| Coverage option | How it works | Provider access | Prescription coverage | Possible additional benefits | Fitness membership | Flex card | Important considerations |
|---|---|---|---|---|---|---|---|
| Original Medicare | Federal Parts A/B | Medicare-participating providers | Add Part D | Medicare-covered services | No standard benefit | No | No annual A/B cost cap |
| Medicare Advantage | Private Part C | Network and service-area rules | Often included | May include dental, vision, hearing, OTC, transportation, or more | Plan-specific | Plan-specific | Check network, formulary, authorization, and MOOP |
| Medigap + Original Medicare | Supplements certain A/B costs | Original Medicare access | Separate Part D usually needed | Generally not MA-style extras | Policy-specific, if any | No standard benefit | Premium and enrollment rules apply |
| Stand-alone Part D | Prescription plan | Pharmacy network | Yes | Drug coverage only | No | No | Check formulary, tiers, and restrictions |
| Hospital indemnity / critical illness | Separate limited-benefit coverage | Contract-specific | Not comprehensive drug coverage | Defined event benefits | No | No | Not Part of Original Medicare or major medical coverage |
HMO and PPO options within Medicare plans New York
HMOs generally use contracted providers and may require primary-care coordination or referrals. PPOs generally allow more out-of-network care at different costs, but noncontracted providers can decline routine care. In dense New York markets, confirm the individual physician, facility, medical group, and practice address.
Review prescriptions, pharmacy networks, prior authorization, and formularies. Medicare Advantage plans have a medical maximum out-of-pocket limit; Part D costs are generally tracked separately. Plan type alone does not determine suitability.
Special Needs Plan guidance within Medicare plans New York
D-SNPs
D-SNP eligibility depends on Medicare, New York State Medicaid status, county service area, and plan rules. The Medicaid eligibility level can affect benefits, coordination, and member costs.
C-SNPs
C-SNP enrollment requires a qualifying chronic condition and county availability. Diabetes, certain cardiovascular conditions, chronic heart failure, and other conditions are examples; offerings differ.
I-SNPs
I-SNPs may serve people meeting institutional or equivalent level-of-care criteria. CMS shows I-SNP offerings in selected New York counties, not statewide. Confirm the facility, service area, and eligibility.
Medicaid, Medicare and Medicare plans New York
People with both Medicare and New York State Medicaid are dual eligible. New York's current Medicare Savings Program benefit levels are Qualified Medicare Beneficiary (QMB) and Qualifying Individual (QI). QMB can help with Part A and/or Part B premiums and Medicare cost sharing; QI helps with the Part B premium. Current state rules and income limits apply.
A D-SNP may coordinate Medicare and Medicaid, but benefits and member costs depend on Medicaid level and plan requirements. Verify eligibility with the New York State Department of Health, NY State of Health, a local department of social services, or Social Security as appropriate. Agents do not decide eligibility.
Extra Help and LIS alongside Medicare plans New York
The Low-Income Subsidy (LIS) and Extra Help refer to one federal Part D assistance program. Eligible people may receive help with premiums, deductibles, and prescription cost sharing. New York notes that MSP enrollment can also lead to Extra Help. O'Neal Insurance Group can explain the process; the government determines eligibility.
Veterans and Medicare plans New York
VA health care and Medicare are separate. Medicare Advantage does not replace VA benefits. Veterans should review prescription sources, non-VA providers, referrals, and emergency or urgent care. TRICARE For Life generally coordinates with Medicare for eligible beneficiaries. Confirm military-benefit decisions with the VA or TRICARE.
Part B giveback and flex cards with Medicare plans New York
A Part B giveback is a plan-specific reduction toward the Medicare Part B premium. It is not a cash payment and does not appear in every county. A flex card has plan-defined approved expenses, allowance, participating retailers, and use rules.
Part B premium reductions, flex cards, and other supplemental benefits are not included with every Medicare Advantage plan. Availability, eligibility, benefit amounts, approved expenses, and participating locations vary by plan and service area.
Dental, vision, hearing, transportation, fitness, over-the-counter, food, utility, and other supplemental benefits may include eligibility, network, frequency, or usage restrictions.
Which companies sell Medicare plans New York
The CMS July 2026 landscape shows offerings in one or more New York counties under Aetna Medicare, Anthem Blue Cross and Blue Shield HP, HealthSpring, Highmark, Humana, UnitedHealthcare, and Wellcare, plus multiple regional organizations. Product and county differ. This does not establish statewide availability or an O'Neal appointment.
Carrier and product availability varies by state, county, ZIP code, eligibility, and plan year. Contact O'Neal Insurance Group to learn which companies and plans are currently available in your area.
Cover beyond Medicare plans New York
- Individual and family health: Major medical coverage separate from Medicare.
- Life and final expense: Life policies pay after death; final expense policies are often compared for funeral costs.
- Dental and vision: Separate specified-service products, not Part of Original Medicare.
- Critical illness: Limited benefits for covered diagnoses.
- Cancer, heart attack, and stroke: Specified-disease policies subject to definitions and exclusions.
- Hospital indemnity: Defined benefits for covered hospital events, not comprehensive coverage.
- Accident: When available, limited benefits for covered accidental injuries.
How a Licensed Agent Can Help
An agent can review Medicare eligibility and enrollment periods; compare premiums and expected costs; check doctors, hospitals, pharmacies, and networks; review drug formularies; discuss Extra Help, New York Medicaid, and MSP routes; compare HMO, PPO, D-SNP, and C-SNP choices; explain plan-specific benefits; help submit an enrollment application after the consumer decides; and review non-Medicare insurance. Government agencies determine public-program eligibility.
How to compare Medicare plans New York in seven steps
- Confirm Medicare eligibility and enrollment period.
- Confirm New York Medicaid status or contact the state or local social services district about applying.
- Enter the permanent residential ZIP code and county, including the correct NYC borough county, for an online instant quote or comparison.
- List doctors, hospitals, pharmacies, all prescriptions, Medicaid or Extra Help status, and veteran or VA use.
- Review premiums, deductibles, copayments, coinsurance, networks, formularies, and maximum out-of-pocket limits.
- Check eligibility requirements and plan-specific benefits.
- Submit an enrollment request only after choosing and reviewing official plan documents.
Frequently Asked Questions
What Medicare Advantage plans are available in New York?
Options vary by county, ZIP code, eligibility, and plan year. Check current records for the permanent residence.
Does Medicare Advantage availability vary by New York county?
Yes. Even neighboring boroughs or counties may have different plans, networks, and benefits.
Can I keep VA health care and enroll in Medicare?
Many veterans use both, but the systems are separate. Confirm VA-related decisions with the VA.
Who may qualify for a D-SNP in New York?
A person must meet Medicare, applicable New York Medicaid, county, and plan requirements.
What conditions may qualify someone for a C-SNP?
Examples may include diabetes, certain cardiovascular conditions, and chronic heart failure, subject to plan confirmation.
Is Extra Help the same as LIS?
Yes. They are two names for the same federal Part D assistance program.
How does a Part B giveback work?
It is a plan-specific reduction toward the Part B premium, not a cash payment.
Does every Medicare Advantage plan include a flex card?
No. Approved expenses, allowance, retailers, and use rules differ.
What is the difference between an HMO and a PPO?
HMOs generally use tighter networks; PPOs generally offer more out-of-network flexibility at different costs.
Can an insurance agent help me enroll?
Yes, after you choose a plan. Medicare and the carrier make the final determination.
Is there a cost to speak with an O'Neal Insurance Group agent?
The agency offers a no-cost consultation with a licensed insurance agent.
What should I have ready before comparing plans?
Bring Medicare information, New York ZIP code and county, providers, prescriptions, pharmacies, coverage, assistance notices, and VA or TRICARE details.
Need help comparing the Medicare plans New York offers?
Call (877) 808-2900 or contact O'Neal Insurance Group online. A licensed agent can review choices based on ZIP code, county, eligibility, prescriptions, doctors, and priorities.
Required Disclosures
Not all carriers, products, benefits, or plans represented by O'Neal Insurance Group are available in every state, county, ZIP code, or service area. Plan availability and benefits may change each plan year. Please call or contact us to learn more about the options currently available in your area.
O'Neal Insurance Group is not connected with or endorsed by the United States government, the federal Medicare program, or any state Medicaid program.
“We do not offer every plan available in your area. Currently we represent 30 organizations which offer over 125 products in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Assistance Program (SHIP) to get information on all of your options.”
New York Medigap rules make the Medicare plans New York offers unusual
Federal law sets the floor for every one of the Medicare plans New York residents can buy. New York then goes further than almost any other state, and if you have only read national advice you are probably underestimating your rights here.
New York has continuous guaranteed issue
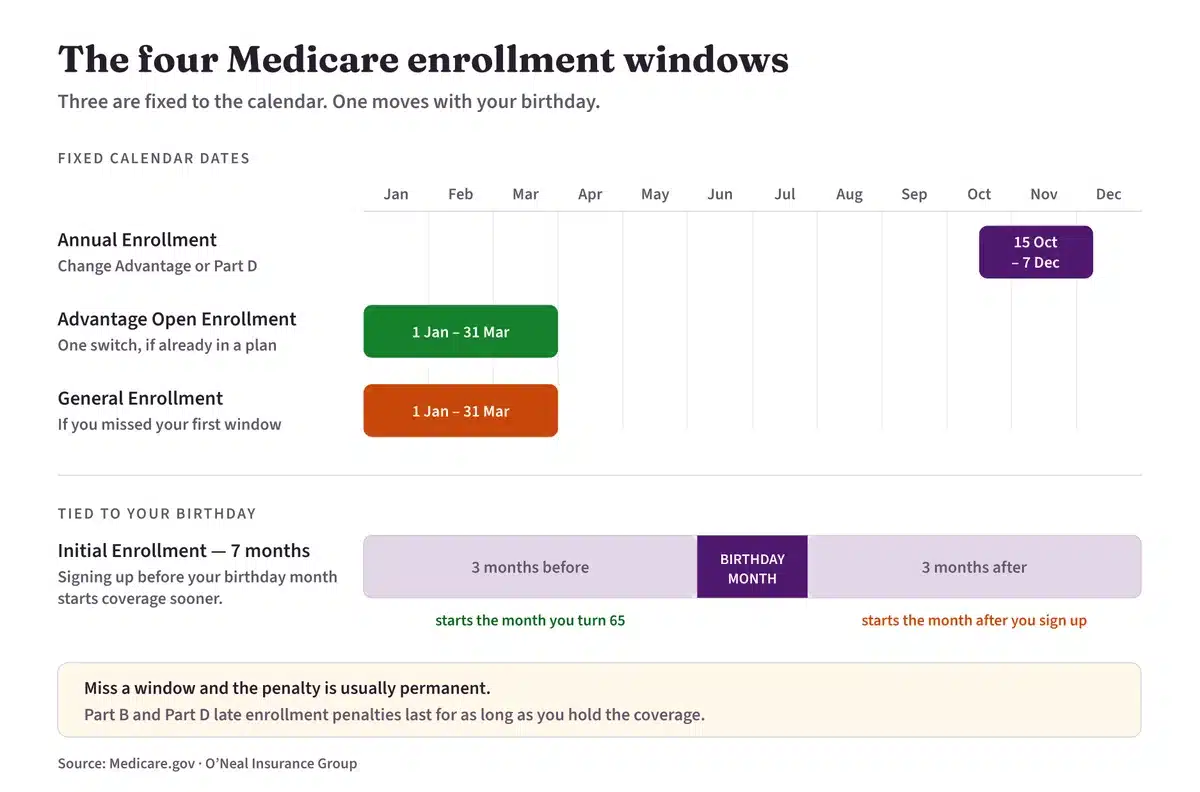
Most states give you one six-month Medigap window at 65 and allow medical underwriting afterwards. New York does not. Under Department of Financial Services rules, an insurer writing Medigap coverage must accept an application from a Medicare enrollee at any time during the year, and may not decline you or charge you differently because of your health.
This is why New York has no birthday rule. It does not need one. Every day is effectively an open enrollment day.
New York community rates its Medigap premiums
New York Medigap premiums may vary only by geographic region. They may not vary by your age or your health. A 78-year-old and a 65-year-old in the same region pay the same rate for the same policy, and your premium does not climb simply because you had another birthday.
One detail to know: a pre-existing condition waiting period of up to six months is permitted, but it must be reduced or waived if you had creditable coverage without a break of more than 63 days. Keep the paperwork proving prior coverage.
The same protection applies under 65
New York's open enrollment and portability rules protect people who qualified for Medicare through disability on the same terms as those who qualified by age, at the same community-rated premiums. Very few states do this.
What this means for your comparison
More than four million New Yorkers were enrolled in Medicare as of January 2026, with roughly 53 percent in a Medicare Advantage plan. Because Medigap is always available to you here, the choice between Original Medicare with a supplement and a Medicare Advantage plan is less final in New York than almost anywhere else. That is worth knowing before you feel rushed.
Rules and enrollment figures behind the Medicare plans New York offers change. Confirm anything that affects a decision with the official sources below.
Official resources you can check yourself
These offices publish the rules behind the Medicare plans New York offers, and none of them sell insurance.
- HIICAP, the New York Health Insurance Information Counseling and Assistance Program gives free, unbiased Medicare counseling with no financial interest in your choice
- New York Department of Financial Services regulates Medigap and lets you verify any agent license
- Medicare.gov Plan Compare lists every plan in your ZIP code and prices them against your prescriptions
- Social Security Administration handles Extra Help, which lowers Part D costs for people with limited income
- SHIP National Technical Assistance Center lists counseling programs in every state
Our plain-language guides cover Medicare Advantage, Medigap, Part D and turning 65, or start with the Medicare overview.
Quick answers about the Medicare plans New York offers
Short answers to the questions New York residents ask most often when comparing the Medicare plans New York offers.
Do the Medicare plans New York offers change every year?
Yes. Across the Medicare plans New York offers, networks, formularies, copays and extra benefits are set for each plan year. Your plan mails an Annual Notice of Change every autumn listing exactly what is different on January 1, and it is the one piece of mail worth reading carefully.
Why do the Medicare plans New York offers differ from my neighbor's?
The Medicare plans New York offers are approved and priced county by county. Two people in the same state can see different lists if they live in different counties.
Can I keep my own doctors on the Medicare plans New York offers?
Only if they participate in that specific plan network for the coming year. We check your providers against the directory before you enroll, and we encourage confirming directly with each office, because directories lag behind reality.
Is there a cost to compare the Medicare plans New York offers with an agent?
No additional fee is charged to you. Agents may be compensated by an insurance carrier when an enrollment occurs, and your premium is the same whether you enroll through an agent, directly with the carrier, or on your own.
Information reviewed August 1, 2026.
Medicare reference charts
One more chart that answers a question we get constantly.