Oregon Medicare guidance
Medicare plans Oregon residents can compare, county by county
The Medicare plans Oregon residents can join are approved county by county, and Oregon adds a birthday rule that lets you change Medigap carriers each year. O'Neal Insurance Group helps Oregonians compare the Medicare plans Oregon offers and other insurance choices available where they live. Licensed agents can explain provider access, prescriptions, costs, and plan-specific rules without pressure.
- Independent Medicare guidance
- Your own personal broker contact
- No-cost consultation
- Licensed agent support
Oregon Medicare Guidance From Metro Portland to Rural Communities
Oregon residents may receive care within the Portland metro, the Willamette Valley, central Oregon, southern Oregon, or the coast. Medicare Advantage and Special Needs Plans use county service areas. Portland crosses Multnomah, Washington, and Clackamas counties, while Salem crosses Marion and Polk counties, making the permanent address essential.
Your Own Personal Medicare Agent Broker can organize the comparison. A Need Analysis records doctors, hospitals, pharmacies, prescriptions, expected care, budget, travel, and priorities. A Scope of Appointment, when required, states which Medicare product categories you agree to discuss. Agents use both to evaluate coverage requirements and comply with federal Medicare marketing rules. Neither is an enrollment application.
Rural residents should consider distance to hospitals and specialists, while people who cross into Washington, Idaho, or California for care should verify network rules. Review coverage annually because costs, networks, formularies, authorization rules, and supplemental benefits can change.
Work with a Medicare Health Insurance licensed insurance agents broker serving Oregon for a current county-and-ZIP review.
Medicare, Health, Life, and Dental Insurance Help in Major Oregon Cities
- Portland — 635,109. Because the city spans three counties, use the exact residential county and check every provider location.
- Salem — 181,779. Residents in Marion or Polk County may see different service areas even within the same city.
- Eugene — 178,618. Lane County comparisons should include local hospital systems, physicians, and pharmacies.
- Gresham — 111,513. Multnomah County residents should verify east-metro providers and specialty access.
- Hillsboro — 111,126. Washington County choices should be checked for west-metro medical groups and hospitals.
- Bend — 107,342. Deschutes County residents should consider central Oregon networks and travel for specialized care.
- Beaverton — 97,842. The city is primarily in Washington County, but exact-address and provider checks remain important.
- Medford — 86,494. Jackson County residents should review southern Oregon networks and any cross-state care.
- Corvallis — 61,499. Benton County residents should check local systems even though Benton is outside the ten largest counties.
- Springfield — 61,431. Lane County residents often share Eugene-area providers, but each practice must be verified.
Population source: U.S. Census Bureau Vintage 2025 incorporated-place estimates, July 1, 2025.
Reviewing Medicare plans Oregon county by county
- Multnomah County — 795,391: Portland, Gresham, and Troutdale residents should verify MA, D-SNP, C-SNP, network, prescription, and benefit availability.
- Washington County — 611,708: Hillsboro, Beaverton, Tigard, and Forest Grove residents should check west-metro networks and formularies.
- Clackamas County — 426,280: Oregon City, Lake Oswego, Happy Valley, and Milwaukie residents should confirm county service areas.
- Lane County — 381,584: Eugene, Springfield, and Cottage Grove residents should review local systems and rural access.
- Marion County — 355,777: Salem, Keizer, Woodburn, and Silverton residents should use the exact county for comparisons.
- Jackson County — 221,795: Medford, Ashland, and Central Point residents should verify southern Oregon networks.
- Deschutes County — 213,072: Bend, Redmond, and Sisters residents should review central Oregon specialty access and travel.
- Linn County — 132,843: Albany, Lebanon, and Sweet Home residents should check local and Willamette Valley providers.
- Douglas County — 111,951: Roseburg, Sutherlin, and Reedsport residents should consider distance, referrals, and county offerings.
- Yamhill County — 110,024: McMinnville, Newberg, and Sheridan residents should verify local care and Portland-area access.
Population source: U.S. Census Bureau Vintage 2025 county estimates, July 1, 2025.
Understanding the Medicare plans Oregon offers
Original Medicare includes federal Part A and Part B. Part A generally covers inpatient hospital care, skilled nursing facility care, hospice, and certain home health services. Part B generally covers physicians, outpatient care, preventive services, and durable medical equipment. Original Medicare has no annual Part A/B out-of-pocket maximum.
Medicare Advantage (Part C) is private Medicare-approved coverage providing Part A and B benefits; many plans include Part D. A stand-alone Part D plan can accompany Original Medicare. Medigap helps with certain Original Medicare cost sharing and does not work with Medicare Advantage. Hospital indemnity and critical illness coverage are separate limited-benefit products.
| Coverage option | How it works | Provider access | Prescription coverage | Possible additional benefits | Fitness membership | Flex card | Important considerations |
|---|---|---|---|---|---|---|---|
| Original Medicare | Federal Parts A/B | Medicare-participating providers | Add Part D | Medicare-covered services | No standard benefit | No | No annual A/B cost cap |
| Medicare Advantage | Private Part C | Network and county rules | Often included | May include dental, vision, hearing, OTC, transportation, or more | Plan-specific | Plan-specific | Check network, formulary, authorization, and MOOP |
| Medigap + Original Medicare | Supplements certain A/B costs | Original Medicare access | Separate Part D usually needed | Generally not MA-style extras | Policy-specific, if any | No standard benefit | Premium and enrollment rules apply |
| Stand-alone Part D | Prescription plan | Pharmacy network | Yes | Drug coverage only | No | No | Check formulary, tiers, and restrictions |
| Hospital indemnity / critical illness | Separate limited-benefit policy | Contract-specific | Not comprehensive drug coverage | Defined event benefits | No | No | Not Medicare or comprehensive health coverage |
Medicare Advantage HMO and PPO Options
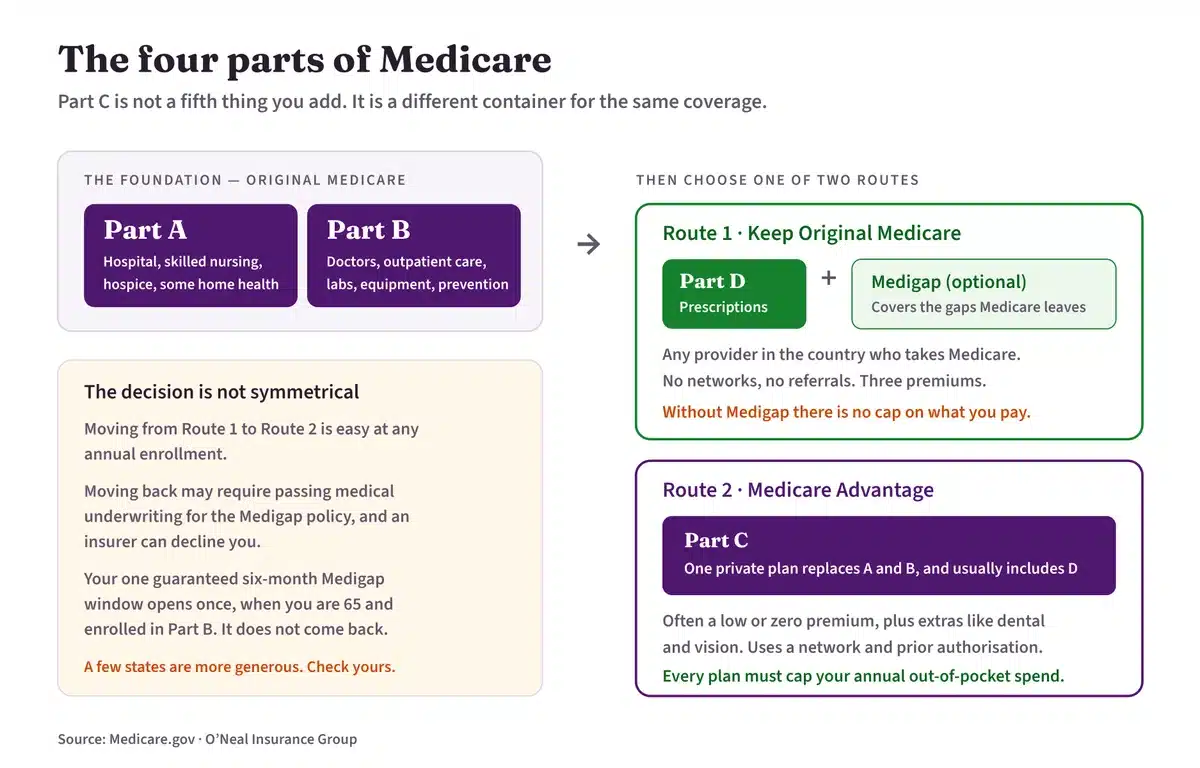
HMOs generally use contracted networks and may require primary-care coordination or referrals. PPOs generally provide more out-of-network flexibility at different costs, but noncontracted providers may decline routine care. Check doctors, hospitals, pharmacies, prescriptions, prior authorization, and formulary rules. The medical maximum out-of-pocket limit generally excludes Part D spending. No plan type fits everyone.
Special Needs Plan Guidance
D-SNPs
D-SNP eligibility depends on Medicare, OHP status, county service area, and plan rules. Medicaid eligibility level can affect benefits, coordination, and member costs.
C-SNPs
C-SNP enrollment requires a qualifying chronic condition and county availability. Diabetes, certain cardiovascular conditions, chronic heart failure, and other conditions are examples only.
I-SNPs
I-SNPs may serve people meeting institutional or equivalent level-of-care requirements. CMS shows selected Oregon county offerings, not statewide service. Facility participation must be confirmed.
Help for People With Medicare and the Oregon Health Plan
The Oregon Health Plan (OHP) is Oregon's Medicaid program. People with both Medicare and OHP are dual eligible. Oregon's Medicare Savings Programs include QMB, QDWI, SLMB, and QI. Oregon calls the QI category the SMF benefit. Depending on category, help may include Part A or Part B premiums and certain cost sharing.
A D-SNP may coordinate services, but county and OHP status matter. Verify eligibility with Oregon ODHS/OHA or Social Security. Agents explain options but do not determine eligibility.
LIS and Extra Help Are the Same Program
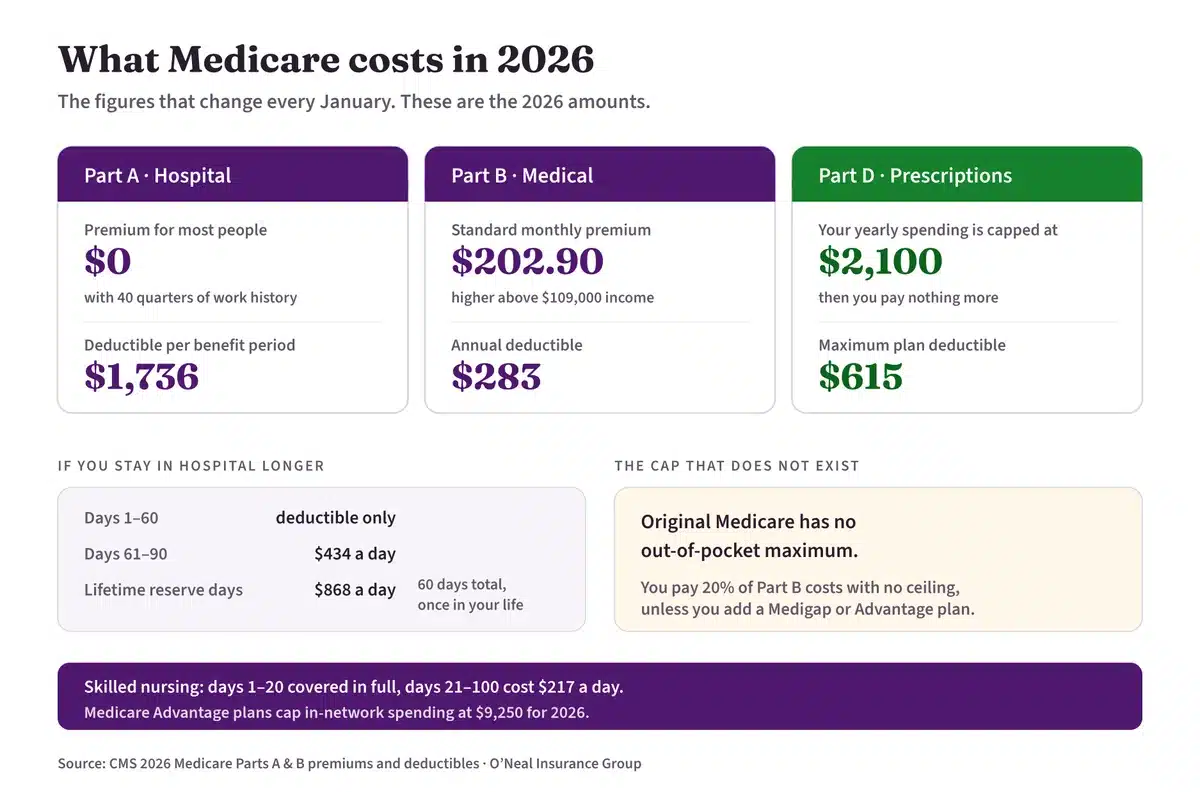
The Low-Income Subsidy (LIS) and Extra Help are one federal Part D assistance program. Eligible beneficiaries may receive help with Part D premiums, deductibles, and prescription cost sharing. Request help understanding the application and plan-comparison process; Social Security or Medicare determines eligibility.
Medicare Guidance for Oregon Veterans
VA health care and Medicare are separate systems, and Medicare Advantage does not replace VA benefits. Review prescriptions, non-VA providers, referrals, and emergency or urgent care. TRICARE For Life generally coordinates with Medicare for eligible beneficiaries. Confirm decisions affecting military benefits with the VA or TRICARE.
Part B Giveback and Flex Card Benefits
A Part B giveback is a plan-specific reduction toward the Part B premium, not a cash payment. A flex card has plan-defined eligible expenses, allowance, retailers, and usage rules.
Part B premium reductions, flex cards, and other supplemental benefits are not included with every Medicare Advantage plan. Availability, eligibility, benefit amounts, approved expenses, and participating locations vary by plan and service area.
Dental, vision, hearing, transportation, fitness, OTC, food, utility, and similar benefits may have eligibility, network, frequency, or usage restrictions.
Which companies sell Medicare plans Oregon
The CMS July 2026 landscape shows offerings in one or more Oregon counties under Aetna Medicare, Devoted Health, HealthSpring, Humana, UnitedHealthcare, and Wellcare, along with regional organizations. Product and county vary. This is not proof of statewide availability or O'Neal appointment.
Carrier and product availability varies by state, county, ZIP code, eligibility, and plan year. Contact O'Neal Insurance Group to learn which companies and plans are currently available in your area.
Additional Insurance Coverage
- Individual/family health: Major medical insurance separate from Medicare.
- Life and final expense: Life policies pay after death; final expense coverage is often compared for funeral costs.
- Dental and vision: Separate specified-service products, not Part of Original Medicare.
- Critical illness and cancer, heart attack, or stroke: Limited benefits for contract-defined diagnoses.
- Hospital indemnity: Defined benefits for covered hospital events, not comprehensive coverage.
- Accident: When available, limited benefits for covered accidental injuries.
How a Licensed Agent Can Help
An agent can review Medicare eligibility and enrollment periods; compare premiums and expected costs; check providers, pharmacies, and networks; review formularies; explain Extra Help, OHP, and MSP routes; compare HMO, PPO, D-SNP, and C-SNP choices; explain plan benefits; help submit an enrollment application after the consumer decides; and review non-Medicare insurance. Government agencies determine eligibility.
How to compare Medicare plans Oregon in seven steps
- Confirm Medicare eligibility and enrollment period.
- Confirm OHP status or contact Oregon ODHS/OHA about applying.
- Enter the permanent residential ZIP code and county for an online instant quote or comparison.
- List doctors, hospitals, pharmacies, all prescriptions, Medicaid or Extra Help status, and veteran or VA use.
- Review premiums, deductibles, copayments, coinsurance, networks, formularies, and maximum out-of-pocket limits.
- Check eligibility requirements and plan-specific benefits.
- Submit an enrollment request only after choosing and reviewing official plan documents.
Frequently Asked Questions
What Medicare Advantage plans are available in Oregon?
Choices vary by county, ZIP code, eligibility, and plan year. Check current records for the permanent residence.
Does Medicare Advantage availability vary by Oregon county?
Yes. Portland-area, central, southern, coastal, and rural counties can have different choices.
Can I keep VA health care and enroll in Medicare?
Many veterans use both, but the systems remain separate. Confirm VA-related decisions with the VA.
Who may qualify for a D-SNP in Oregon?
A person must meet Medicare, applicable OHP, county, and plan requirements.
What conditions may qualify someone for a C-SNP?
Examples may include diabetes, certain cardiovascular conditions, and chronic heart failure, subject to plan confirmation.
Is Extra Help the same as LIS?
Yes. They name the same federal Part D assistance program.
How does a Part B giveback work?
It is a plan-specific reduction toward the Part B premium, not a cash payment.
Does every Medicare Advantage plan include a flex card?
No. Eligible expenses, allowance, retailers, and use rules differ.
What is the difference between an HMO and a PPO?
HMOs generally use tighter networks; PPOs generally provide more out-of-network flexibility at different costs.
Can an insurance agent help me enroll?
Yes, after you choose a plan. Medicare and the carrier make the final determination.
Is there a cost to speak with an O'Neal Insurance Group agent?
The agency offers a no-cost consultation with a licensed insurance agent.
What should I have ready before comparing plans?
Bring Medicare details, Oregon ZIP and county, providers, prescriptions, pharmacies, coverage, assistance notices, and VA or TRICARE information.
Need help comparing the Medicare plans Oregon offers?
Call (877) 808-2900 or contact O'Neal Insurance Group online. A licensed agent can review choices based on ZIP code, county, eligibility, prescriptions, doctors, and priorities.
Required Disclosures
Not all carriers, products, benefits, or plans represented by O'Neal Insurance Group are available in every state, county, ZIP code, or service area. Plan availability and benefits may change each plan year. Please call or contact us to learn more about the options currently available in your area.
O'Neal Insurance Group is not connected with or endorsed by the United States government, the federal Medicare program, or any state Medicaid program.
“We do not offer every plan available in your area. Currently we represent 30 organizations which offer over 125 products in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Assistance Program (SHIP) to get information on all of your options.”
The Oregon birthday rule and the Medicare plans Oregon residents can switch to
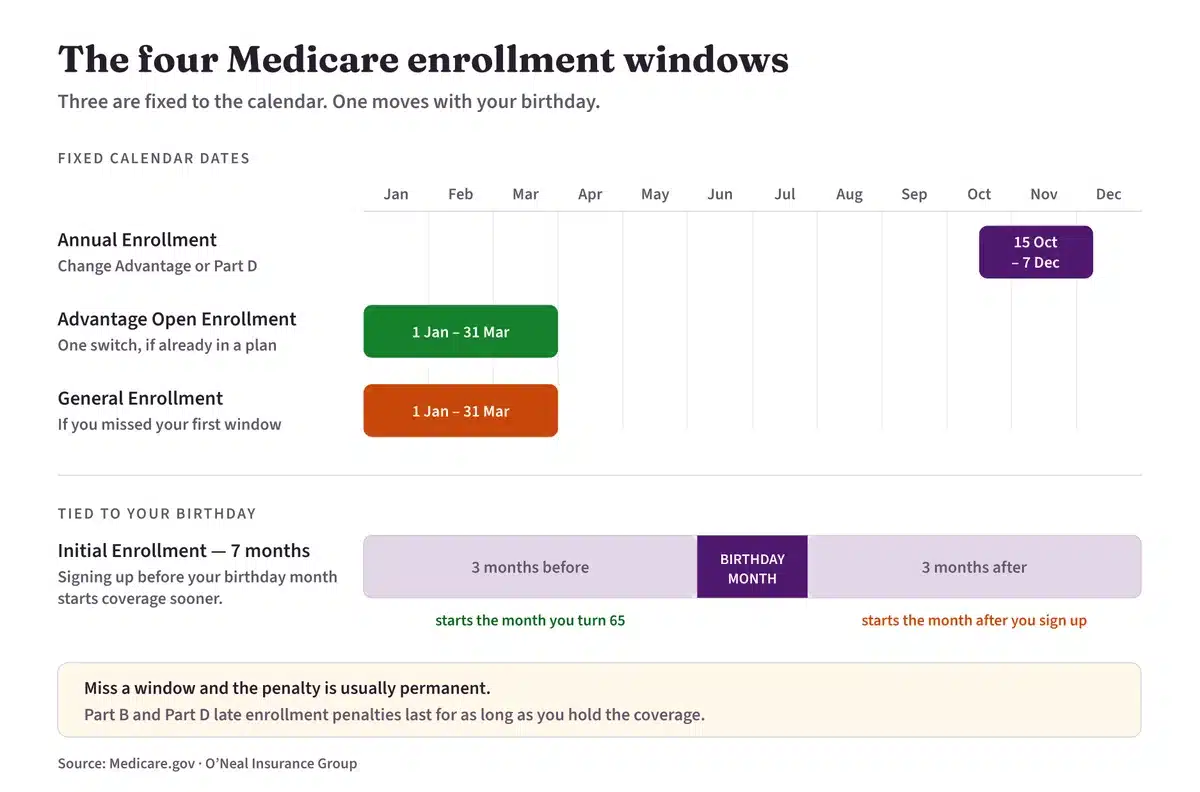
Federal law sets the floor for every one of the Medicare plans Oregon residents can buy. Oregon adds two protections that are among the strongest in the country.
Oregon has a Medigap birthday rule
Oregon Administrative Rule 836-052-0143 gives Medigap policyholders an annual window to cancel their existing policy and take another with the same or lesser benefits, without medical underwriting. You may move to a different insurance company, which is the part that makes it valuable.
- The rule text runs from 30 days before your birthday through 30 days after it
- You may switch to a different insurance company
- The new policy must carry the same or lesser benefits
- The rule is written around anyone enrolled in a Medigap policy, with no age floor stated
One honest caution. Oregon's own consumer FAQ page and several national websites describe the window differently, some saying it begins on the birthday rather than 30 days before. The administrative rule is the authority, but because the difference could cost you the window, confirm your exact dates with the Division of Financial Regulation before you rely on them.
Oregon caps under-65 Medigap premiums
Oregon gives people who qualified for Medicare through disability a six-month guaranteed-issue window at Part B enrollment, and then does something most states do not: it caps their premium at the rate charged to a 65-year-old. Oregon also extends guaranteed issue to people moving in from states with no under-65 requirement.
What this means for your comparison
Around 944,000 Oregonians were enrolled in Medicare at the most recent federal count, with more than half in a Medicare Advantage plan. Because Oregon lets you change carriers each year, a Medigap premium that has drifted upward is worth re-shopping annually rather than tolerating.
Rules and enrollment figures behind the Medicare plans Oregon offers change. Confirm anything that affects a decision with the official sources below.
Official resources you can check yourself
These offices publish the rules behind the Medicare plans Oregon offers, and none of them sell insurance.
- Oregon SHIBA (Senior Health Insurance Benefits Assistance) gives free, unbiased Medicare counseling with no financial interest in your choice
- Oregon Division of Financial Regulation regulates Medigap and lets you verify any agent license
- Medicare.gov Plan Compare lists every plan in your ZIP code and prices them against your prescriptions
- Social Security Administration handles Extra Help, which lowers Part D costs for people with limited income
- SHIP National Technical Assistance Center lists counseling programs in every state
Our plain-language guides cover Medicare Advantage, Medigap, Part D and turning 65, or start with the Medicare overview.
Quick answers about the Medicare plans Oregon offers
Short answers to the questions Oregon residents ask most often when comparing the Medicare plans Oregon offers.
Do the Medicare plans Oregon offers change every year?
Yes. Across the Medicare plans Oregon offers, networks, formularies, copays and extra benefits are set for each plan year. Your plan mails an Annual Notice of Change every autumn listing exactly what is different on January 1, and it is the one piece of mail worth reading carefully.
Why do the Medicare plans Oregon offers differ from my neighbor's?
The Medicare plans Oregon offers are approved and priced county by county. Two people in the same state can see different lists if they live in different counties.
Can I keep my own doctors on the Medicare plans Oregon offers?
Only if they participate in that specific plan network for the coming year. We check your providers against the directory before you enroll, and we encourage confirming directly with each office, because directories lag behind reality.
Is there a cost to compare the Medicare plans Oregon offers with an agent?
No additional fee is charged to you. Agents may be compensated by an insurance carrier when an enrollment occurs, and your premium is the same whether you enroll through an agent, directly with the carrier, or on your own.
Do I have to switch plans every year?
No. If your plan still covers your doctors and prescriptions at a cost that works, staying is a good answer, and it is a common result when we review the Medicare plans Oregon offers. Reviewing annually still matters, because the plan changes even when your situation does not.
What should I have ready before comparing Medicare plans Oregon?
Your Medicare card, the names of every doctor and specialist you want to keep, every prescription with its exact dose, your preferred pharmacy, and your current plan's Annual Notice of Change if one has arrived.
Information reviewed August 1, 2026.